Curious about upgrading?
Wondering where to start?
Complex questions that need answers?
Is there a better structure for you?
"They managed to navigate my complex expat income and even got my Google RSU income approved as well."
"I highly recommend Alcove to anyone looking for a mortgage broker who is responsive, trustworthy, and truly cares about their clients. Thanks again to the whole team for making the process such a positive experience!"
"As founders, we're constantly jumping between things so having a partner that handled the details & made the process super clear made the buying process breezy for us. Very happy with the experience!"
“It almost felt like it was his responsibility to make it clear to me, not my responsibility to understand it.”
“I've been pretty much fully leveraged the whole time. So the sounding board on that, in terms of what was achievable, what wasn't — I think trust is just built along that.”
"Alcove has been a great partner. They look after my audience properly, keep things simple, and deliver real value. I’ve got full confidence referring clients knowing they’ll get honest, straightforward advice."
"Property is one of the biggest financial decisions people make. Alcove stood out because they take a strategic approach to lending - helping clients structure property and debt decisions in a way that genuinely supports their broader financial plans."
Adapted from audio. This article is a written adaptation of the original podcast episode. Sources and dates are shown with each figure.
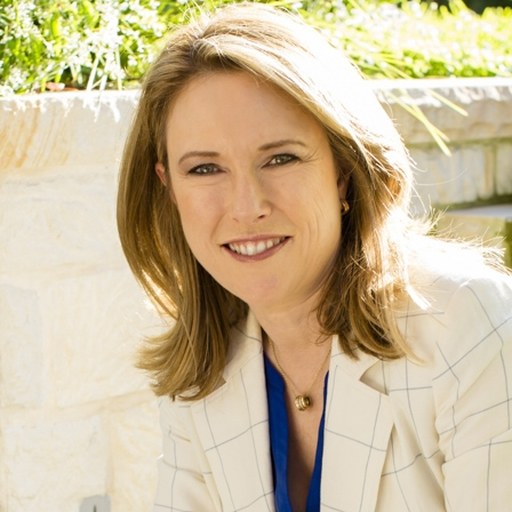
Co-host of The Elephant in the Room. Real estate agent, buyer's agent and buyer's agent mentor, co-host of Foxtel's Location, Location, Location Australia, author of Auction Ready and co-host of Your First Home Buyer Guide.

Catherine Simons on Where Tax Advice Belongs in a Property Plan
WSC Group's Catherine Simons has prepared property investor tax returns for close to 20 years. She explains why ownership and borrowing decisions are hard to unwind once a property is bought.
In this episode, we're talking with Catherine Simons from WSC Group, and we're going to explore the wonderful world of tax and property investment, specifically where tax advice needs to fit into the property planning process and the consequences of getting it wrong, or what can happen when you leave it too late to get advice.
Welcome to the elephant in the room. This is the podcast where we love to talk about the big things in property that never usually get talked about.
I'm Veronica Morgan, real estate agent, buyer's agent and buyer's agent mentor, co-host of Foxtel's Location Location Location Australia, author of Auction Ready and co-host of Your First Home Buyer Guide.
Hi, I'm Chris Bates, mortgage broker, currently ranked number three in the MPA Top 100 Mortgage Broker Awards. Before we get started, everything we talk about today is not personal advice, and we recommend you engage the services of a licensed and experienced professional.
Our guest today is Catherine Simons, the Managing Director of WSC Group. Catherine specializes in rental property investment and small to medium-sized business advice. And with 19 years of experience in public practice accounting, Catherine works with her clients to assist them to build more profitable businesses
and create more personal wealth through business advisory and taxation services. Her focus is to achieve the best outcome for a client every time, which is why we like to speak with her.
Now, she has a very solid understanding of the challenges of property investment and can assist clients with advice on how to build their wealth from the ground up. She also manages the continuous improvement and internal business processes within her business, and this gives her the practical experience in running business day-to-day
and the knowledge to assist small to medium-sized business clients. So that's a bit of a roundup on who Catherine is. Welcome and thank you so much for joining us. And I'm sure that our listeners are going to really get a lot out of this conversation. So thank you, Catherine.
Thank you for having me.
Thanks, Catherine. You can never have too many episodes around tax. And I always get very excited by, you know, talking about these episodes because there's just so much to cover and I want to cover today. But I mean, what came first, sort of your profession or your love of property?
I mean, or did you, you know, as an accountant, just fall in love with property over time?
Yeah, definitely the profession. So, I started out as a very eager 18-year-old and didn't know anything about property investment, didn't know what the definition of negative gearing was and was thrown into the gauntlet of preparing hundreds of property investor tax returns.
for a very broad range of people, moms and dads with fairly moderate incomes who are just looking to provide for their retirement, and then very wealthy people alike who are looking to access the tax benefits associated with negative gearing.
But over time, just seeing how much people gained out of their property investment portfolios and how beneficial that's been to people, my own love for property has grown. And I've owned different properties at different times, residential, commercial, we do a bit of everything here. So yeah, it's been a learning journey.
And I have to say, despite having done this for nearly 20 years in July, I am still learning something every month.
I think that's one of the best ways to learn, right? I mean, it's one of the benefits of doing what we all do, right?
Is we get to ask people a lot of questions about what they're doing and what they're up to and, you know, and not the story you say at a barbecue, the truth of the story. What exactly did you pay? What exactly did you buy? Yeah. How's it actually performing for you?
And, you know, by looking at, you know, client after client for many years, you get so many learnings.
Is this sort of, before we go to other things, just some things that you've sort of picked up that, you know, sort of myth breakers or things that you sort of your own property philosophy that you've developed by just looking at other people?
Yeah, absolutely. I'd say there is one very key learning, and it's something I reference with clients pretty frequently, and that is that there are ways to lose money on property.
I think being in Australia, you can inadvertently live in this bubble where you think nobody ever loses money on property, and you might be able to hide that from your friends, but you can't hide it from your accountant. If you've lost money, we're going to know about it.
So I think the key learning over time is is just that property is a long-term investment and the best way to lose money on a property investment is to buy one that you're forced to sell.
If you get yourself into a situation where you have to sell a property at a time which is not of your choosing, it is undoubtedly going to be the worst time to sell. That is so interesting.
And in fact, you know, we've got a bunch of other questions for you, but I'd love to dig further into this idea about how you can lose money in property because often people just assume it's, oh, well, if I sell it and I lose money.
But what you're talking about there in that being forced to sell, there's a number of things. One is the opportunity cost of basically selling out of an asset you may never get back into and Secondly, is that it might be a good asset that you're forced to sell.
Thirdly, is that if you're forced to sell, the timing of your sale is not at your choosing. So you're not able to pick market conditions or even the right tax year for you or anything like that.
Can we dig a bit further into other areas or even further onto this particular issue in terms of how you've seen people lose money in property? And the things that aren't talked about, things that, you know, opportunity costs, for example, is not often talked about.
No. Yeah, and you're right. There's some of those tax matters and those sorts of things, but often it's the simple stuff like the cost of transacting. It's not cheap to buy and sell property in this country.
By the time you've paid stamp duty, had a few reports prepared, and then exiting, you've paid your agent, you need to have made a pretty solid rate of capital growth. to pay yourself back in the short term.
So if you're looking to buy and sell property in a timeframe that's only a few years, it's pretty easy to get those numbers wrong with the cost of transacting. But in addition to that, like you mentioned, being forced to sell in a tax year that's not ideal, perhaps that's not a loss.
Maybe you still make some money. But if you're adding a capital gain to your already very high income, you are paying a rate of tax that's probably not very palatable.
And with a little bit of planning and potentially deferring the sale of a great asset like that into your retirement years, you may be able to access the benefit of your lower tax rates rather than just adding your capital gain to your taxable income that might already be pretty high.
you just sort of touched on something. I mean, people come to us all the time and, um, you know, and they don't mean to, they just created a view on, you know, they've spoken to a friend of a friend or a parent or something like that.
And they've said, you can get borrow money, no problems, you know, six times your salary, or you can borrow on a casual income or whatever it might be to have these like beliefs that you can do.
Is it, what are some of the things when you think people come into you and then, Oh, I can definitely buy my home in a super fund. Like, um,
What are some of the things where you think people come to you and that you just have to kind of maybe explain the real rules around tax in relation to property?
Yeah, well, the super fun thing we could talk about all day, but that gets a little bit niche. Trusts are probably the big one. You know, I think every day I have an appointment where someone asks me if they should purchase a property in a trust. And for the right person, they're fantastic.
I've got to trust myself. But for property, they present some pretty unique challenges and they are more expensive than owning a property in your own name.
So, if you are a typical employee with a high salary who wants to get the access to the negative gearing benefits and all of those things, a discretionary trust is not going to do you any favors.
And depending on where you purchase a property, you're potentially costing yourselves thousands and thousands of dollars in additional land tax each year just for the privilege of owning a property in a trust. If it's positively geared, there's some great benefits. You've got the discretionary income benefits associated with the trust.
If you need some asset protection, they can jump in and help you. They're great. But owning a trust for the sake of owning a trust and having your property in there, I'm not a big fan.
I had a client today, literally, on that exact point. It's an interesting case study, right? Because it's just topical. He's an anesthetist. Earned a lot of money, right? Close to a million bucks.
And he's got a house, but he's like, I've got pretty low debt. The LVR on the property is pretty low, and he's on a great income. He's got heaps of capacity left over and it makes sense to do some further investing. He's in a job where there is a bit of a risk.
There's a bit of issues with your job and getting sued, etc. There's a desire to protect himself with a trust, but
You know, if he is going to go and buy a property, there's, you know, mostly he might do it in Victoria, you know, and there might be quite a big negative cash flow, he's still got a bit of home debt, so, you know, he probably wants to pay that off because it's non-deductible, and so, if he wants to buy shares, it's going to be a negative cash flow there as well, so...
You know, it's really hard just to, you know, you've got to really weigh that up, right? The asset protection benefit versus the impacts of, you know, running a trust in a negative cash flow.
Do you think that a lot of accountants just quickly go to the trust for the asset protection, but don't explain that? Is that the real dilemma that people really need to understand?
My experience with accountants isn't usually that the accountant's the one pushing the trust, but for someone like that, there could be some great benefit. Like you've identified, they're at much higher risk potentially in their occupation than some other people of being sued.
But depending on how their employment relationship is structured, if they're self-employed, so if you've got someone who's in private practice and is employing other people and has other people operating within their medical practice, then There are ways we can emulate the negative gearing structure for a person like that.
So typically, people like that, there are avenues that we can explore if they've got a business trust or some sort of similar structure. It's more the typical employee without that asset protection consideration where the trust can end up being a really costly overkill.
Gotcha.
What sort of got me thinking too when you're talking about trust is that it might work at different stages of your life, but once you decide on the ownership structure and the borrowing structure for that matter with a property, you're pretty stuck with it, aren't you?
I mean, without significant cost to get out of it and change it. So how, I guess, as an accountant in this piece, how do you go about working out the right structure that will sort of last the length of ownership of a property?
I think that primarily comes down to understanding what's important to your client.
And then we talk about what the likely outcome is. What are we likely to do over the next 10 to 15 years? When are you likely to sell the property? How negatively geared is it to start with? And how long do we foresee that lasting?
And then we go through what happens if the property doesn't perform the way we expect it. and just understand the outcomes of each of the ownership structures. For most people, they leave pretty comfortable with whatever they've chosen. And that's the main thing.
You need to understand you don't want to be there in five years' time kicking yourself that you didn't choose another available ownership structure.
So just being able to talk through the pros and cons of each and just contrast them so that they can sit back and say, okay, how do I really see my life unfolding and which one of these is going to deliver me the best outcome on that basis?
So I was going to ask you at what point should a property investor engage an accountant, but you just answered that question before you buy an investment property, right? Yeah.
Pre-purchase, absolutely. If you're not having a conversation pre-purchase, there's not a lot we can do for you after purchase. I have no tricks that relate to stamp duty, none whatsoever.
However, I would imagine that most people do go ahead and buy their first investment property without getting an accountant's advice. Would that be a fair assumption?
Yeah, most. I mean, I guess I see the ones that don't. I see the ones that do come and chat to us before purchase. But even amongst our clients, the ones that have come after they've purchased the investment property probably outweigh the ones that come before. So yeah, probably most.
And I mean, a lot of people become accidental property investors because they've decided to rent out a place that they've lived in or done all of those things. And then they've given no consideration to ownership.
No, no. Or the debt and borrowing and all that sort of thing. I mean, you talk about it's easy to lose money in property.
That's another way you can lose money, literally in the sense that if you haven't forethought those options, what might happen, and you do set things up in a way that you could have set things up differently without needing to worry about trusts or anything complicated like that. I'm thinking more borrowing structures. Yeah.
Then, you know, you're sort of hamstrung. And I know myself and my own investment properties, one in particular that I – I didn't understand back then. My accountant obviously didn't take the time to educate me or perhaps I wasn't listening. I don't know.
But at the end of the day, I didn't understand then the difference between having an offset or a drawdown. Yeah, a redraw. A redraw, yeah. I didn't understand the difference. And of course, I dumped a whole bunch of cash from the sale of another property into the redraw, not into an offset.
And, you know, and then ended up paying, you know, investing, so renovating that property and so on. And now looking back, I know that I left a lot of money on the table because I didn't have the right structuring around all of that.
So let's talk a bit about that because this is sort of the hidden thing.
ways people lose money in property, right? Absolutely. I mean, you've hit the nail on the head.
The main thing that we talk to people about when the future is a little bit uncertain, so you've bought a property, you're living in it, but you've not put your roots down, you're not in your forever home and you know that to be the case.
The gift of providing yourself some flexibility for the future is enormously helpful.
So just owning, having an offset account and not making any discretionary payments off the principal, putting all of your excess funds into that offset account to give you the flexibility that if you do decide to go and buy that forever home, Or you just decide to move states or whatever that is.
You can pick that money up out of the offset account and use that for the deposit on the next one. And you haven't lost any tax deductibility on the underlying loan.
For the most part, when people are living in properties, because of the access to lower interest rates, they'll probably still choose to do a principal and interest loan. But when you look at the principal repayments on a typical 30-year homeless,
loan in that initial period, you're not paying that much down.
The monies you're contributing to that offset account are likely to be much bigger and they'll leave you with that residual tax benefit that you otherwise, as Paul Veronica learned the hard way, otherwise forego many thousands of dollars of tax benefit in the future.
What's some sort of other things, I mean, that you find that people have, you know, maybe not done it right. You know, they thought that, you know, maybe the six-year rule, I think there's a lot of misconceptions around, you know, what's deductible, you know, getting CGT relief, you know.
I mean, what's your sort of other things where people are making mistakes, maybe not keeping the tax records on, you know, investment properties and just really missing lots of deductions.
There's lots of things that people get wrong, I guess, with tax that, you know, on retrospect, they wish they, you know, did things differently.
Yeah, absolutely. The six-year rule, there's plenty of errors and misconceptions there. But I guess the key one is taking the time when you decide to sell a property that's eligible for the six-year rule to look at what the market valuation of that property was the first time you earned rental income.
Because that's actually the cost base for the property in that situation rather than what you paid for it. So, I'll take you through a quick scenario of someone who gets that terribly wrong.
Let's say I've bought a property and I live in it for five years and then I decide to start renting it out. Yeah. And I go and immediately purchase another property to live in.
And then I live in that property for five years and rent the old principal place of residence out for that whole five years. And I get to the end of that 10-year period and I sell my first home and I go, that's okay. I rented it for less than six years.
I don't have to pay any capital gains tax on that. That's absolutely true. But I can only have one principal place of residence at a time. Now, obviously, the value of money now is worth more than it will be in the future.
So there's some benefit to just saying, okay, well, I don't want to pay any tax now. You know, tax on the place I'm living right now is tomorrow's problem.
But I've got the ability to use the market value substitution rule to find out what that property was worth the first time I rented it out and actually see how much that capital gain is when I'm actually selling. So I get the benefit of hindsight.
So let's say I purchased the property for 700, and by the time I sold it, it was worth a million dollars. Sorry, by the time I rented, it was worth a million dollars. And then by the time I sold it, it was only worth $1.1 million. I've only got $100,000 capital gain.
And assuming I've been a resident of Australia for tax purposes for that whole time, I'm also going to get a 50% discount. So I'm only going to pay tax on $50,000.
If the home that I've moved into when I started renting out home one has gone up in value by $500,000, it's a no-brainer. Take the hit, keep your main residence exemption, and move forward with your life.
So just taking the time to not just take the pub tax advice about what's good for you and actually sit down with your accountant and work through the scenario and taking the benefit of hindsight and learning what you've made can save you thousands of dollars long term.
Oh, my God. I've never even realized that that was even an option. But I can so see it. Absolutely. And people will go, they'd take it now. I don't want to pay tax now.
And a lot of people, they don't sort of understand compounding and they also don't understand that a bigger asset or the different assets have different rates of capital growth or different properties have different rates of capital growth. And if they have never given that any consideration, it wouldn't even occur to them.
No, and especially you're likely to buy a bigger house, aren't you? When you're doing that upgrade, you're likely to go from something smaller, which by its nature is not going to make as much in capital growth than the asset that you've purchased subsequently.
Yeah. So it's not really about percentages there. We're talking about actual dollar values and the impact. Have you seen anyone do that?
Yeah.
Don't choose to pay the tax now to defer it later. No, no. Choose to not pay the tax now. Yeah, absolutely. People love to put off their problems to another day. Absolutely. Yeah, yeah. It's human nature. It's the elephant. Exactly right.
I mean, the rules around depreciation are always changing. This is the one that I think that... Yeah, I think people miss it a lot, right? They're just, oh, it's not properly, I don't know if I didn't bother getting a depreciation schedule, but, you know, or they think they haven't got a gain.
They have got a gain because they haven't factored in that depreciation reduces the cost. Do you find that this is one that you've constantly, it's a bit of a mind bender for clients that you've got to really explain it to them and they get it wrong a lot?
Most of our clients are pretty good at taking guidance, but it's certainly something we ask about with every property because you're right. Obviously, if you've purchased a property that was built in the 70s, inherently, there's no building depreciation left. We've got nothing left there.
But we need to go that next step and say, has it ever been substantially renovated? Because the likelihood is the older a property is, the more likely it's had some substantial renovations. They don't need to have the detail about those substantial renovations.
We've got lovely quantity surveyors that will go out and work that all out for us.
But the latter point you touched on, which is the effect on your cost base of depreciating a property, is something that comes up with clients quite a lot because they tend to not understand the effect of claiming those dollars of depreciation when you go and sell.
And the effect of that is every dollar you're claiming of depreciation is essentially a dollar of the purchase price because you paid for the building. And the nature of depreciation is it's a notional decline in value of the building. So we're getting tax benefit for part of what we've paid for up front.
So that's going to come off the cost base. The reason it's still typically a benefit is A, money's worth more now today than it is going to be in the future. And generally, we're getting a 50% discount on the capital gain. So, we're getting the full dollar deduction when we claim the depreciation.
And we're only really losing half the benefit when it gets added to our capital gain. So, typically, it's still the best thing for people. It's just a bit of a sting if you don't understand that it's going to come off your cost base.
Yeah, it's a definite sting.
I feel, I mean, all of these things over many years in the business I've become aware of, but individuals, if they're not spending time talking about property day in, day out, could get to the point of selling an investment property and have absolutely no idea and happily sort of claiming those deductions all the way through.
I think, too, that there's a lot of misconception about negative gearing, negative cash flow, positive cash flow, all of that sort of stuff.
In fact, I haven't had to answer this question for some years, but we used to get people that would call into my buyer's agency business and say, I want to buy a positive cash flow investment property. And because we buy in Sydney, I'd be going, that's great.
Have you got like a 50% deposit? 50. Might need to be 60.
Might be more now. Sorry.
And they're like, what do you mean? No, I want to borrow 105% and I want positive cash flow. Well, they don't sort of, you can't. They don't exist in Sydney. But there is a lot of attraction, I guess, this idea of, you know, buying an investment probably doesn't cost me anything.
Because it doesn't cost me out of my cash flow, it feels like it's not costing me anything. But in reality, and we're talking about opportunity cost, I've got lots of examples and case studies. You can see it's cost people by not buying a good asset.
Can you sort of put some, I guess, some accounting lens or discuss that through what you see in your practice? Yeah.
So, I mean, we have over the years seen the odd unicorn where someone has managed to borrow the full purchase price, happened to buy in a market where the yield's really good, and we've hit that golden low point of the interest rate cycle.
So, between all of those things and the fact that they've got some depreciation, the property might be positively geared after tax benefits. But I've probably seen that five times over the several thousand property investments that I've seen over the last few years. So, it doesn't happen often when you're borrowing the full amount.
But as you say, you know, at the end of the day, the main reason most people go into property investment is for capital growth.
And the reason for that in this tax system is that like we've talked about with our 50% discount, the money you make on assets is taxed more favorably than the money you make via income. So you walk away with just more of those proceeds.
So typically, we encourage people to focus on purchasing the best asset that they can afford and that they can afford to hold long-term rather than focusing too much on the tax and let us worry about the tax.
We'll make the tax work around whatever it is you choose, but make a good investment decision. Don't make a decision around tax because usually when you're chasing that tax benefit, you're you're buying into a brand new area that's being developed.
So you can get a really high depreciation property and your capital growth can sometimes be quite deferred because the market's got a lot of property available short term. So there's not a lot of upward pressure on your capital growth. There's not a lot of upward pressure on your rental income.
So you're often stuck in a suppressed rental environment for a period of time. Sometimes that works really well. Sometimes those areas really take off. that you've got to look into all of the dynamics in the area. But the key thing is don't spend your whole life chasing some extra tax benefit.
Spend the time chasing the best assets that you can afford and then hire someone really good to look after the tax stuff.
And I mean, have you ever seen like thousands of properties? And I think that's sound advice, right, by the way. That's exactly the, we all believe in that. And our listeners would definitely believe in that too, probably.
So, but I mean, when you look at those portfolios, is there sort of, have you brought, you know, built your own sort of Catherine's philosophy on property? What makes a great asset? Like, you know, you mentioned there are new developments, sounds like.
which we agree with, but is there something in your mind that you go, okay, this ticks all the boxes. When I look back at all the clients I've seen, the ones who have done the best, the ones that have got the best returns typically have bought these type of properties.
Well, they've typically stuck to the capital city markets. The real horror stories you see are in very different markets. So again, as Australians, we think property always just goes up. There are parts of Australia in the regional areas where that doesn't happen all of the time.
You know, you pull the main income source out of a particular mining town and the property does some pretty crazy things. So, look, my philosophies are just if something sounds too good to be true, it is too good to be true. That's my main philosophy.
But otherwise, I tend to just stick to those sound principles around infrastructure, schools. You know, all of the typical stuff, the boring stuff that everybody tells you. I think the boring stuff is usually the most effective.
And then occasionally, a client comes with one of those too-good-to-be-true stories and buys the asset, and it does exactly what they expect it to do, and they come in and say, I told you so.
Because sometimes those things, risk and return, sometimes they take the risk and they get the return, and a lot of the time they take the risk and they don't get the return.
So it's just being able to look at those people who happened to buy cryptocurrency at exactly the right time and then sell cryptocurrency at exactly the right time and understand that that still doesn't make it a good investment philosophy.
No, and I'm always curious with those. Those people too like to hang around and say, what do they do next? Because often there's a huge amount of overconfidence. They actually don't put down their success to luck, which is usually what it is completely.
They think it's their own good judgment and the fact that they are willing to take risks and that the taking of the risk is actually what gets the payback, not the actual risk.
um the lucky side of things so when we sort of get into risk actually um a lot of people do get into property investment then then they start they buy a few properties and then they start to get you know they get more of an appetite for risk you know this is feeling good i'm doing well i feel like you know i feel like i can do more here and then they venture into property development
Now, is this something that you've seen in your business where you've got these clients that are more active or even if they're doing flipping, they get more active in their property investment? I'd be really keen to know some of the lessons I guess you've learned from observing their financial outcomes over time.
Yeah, and we've seen that go well and we've seen that go badly. A lot of people decide to give flipping or renovating or building for sale or making duplexes a go once they've done well out of property. The key lesson there is to not leave yourself short of cash.
So the best development to go into is one, again, that you're not forced to exit at a particular time because markets do turn, build costs go out, all of those things happen.
If you've got the money to ride that out and say, get to the end of a development that you had intended to sell and say, hey, this is not the right time to sell. I'm going to pop this on the rental market for a few years and come back to it later.
then you probably aren't going to find yourself in too bad a position as long as you've chosen an asset that's in a great area. You can ride through most things.
But the tricky bit is if you go down that development route and you've really cut your margins fine, you've done your feasibility, but you haven't allowed for the 40% overrun in costs there,
And the 5% dip in prices and the seven interest rate rises and all the things that can happen during the course of the development. If you haven't allowed for those things in your feasibility and given yourself that breathing space to sell in a different market, then yeah, it can go really wrong.
And you might end up with a bank foreclosing on your property instead of being able to sell yourself. or should I buy before I sell, or the other way around.
You can connect with me and access all of the tools that I've created to help you make better property decisions at veronicamorgan.com.au. And there you will find resources for first home buyers, details about my buyer's agent mentoring program.
You can connect with my Sydney-based property management and buyer's agency teams, Australia-wide vendor advocacy, or ask me for introduction to the small group of buyer's agents that I would personally recommend across the country. That's veronicamorgan.com.au.
If you're looking to buy your first home, thinking of upgrading to a new one or purchasing an investment property anywhere in Australia, we would love to carefully guide you through this journey and importantly, get the finance right. Reach out via my website, alcove.com.au.
Have you, obviously, interesting thing, I started like years 18 as an accountant and, you know, part-time uni, you know, the traineeship, $30,000 a year, you know, doing bazzes and, you know, personal tax returns, etc.,
And, you know, I didn't probably grasp that tax can get interesting at that point. I was probably so low on the ladder that I just thought I was just going to be like this for the rest of my life.
But, you know, tax can get interesting the further you get up and the more interesting clients you get with. I mean, obviously tax rules are always changing, right? And, you know, your strategy around tax is changing. What's some of the things that...
I think you're looking at things differently coming into 2025 and over the next few years that you didn't think you were advised on more. Is it still a lot of bit of the true principles are still there?
It's just that the ATO is putting more of a focus on certain things and we've got to be concerned about different structures. I mean, what's some changes coming, I guess?
The foundational stuff's still the same. I mean, that hasn't changed. I was going to make a joke about your boss being pretty generous, paying you $30,000 a year while you were training. 13, 13. 13. Oh, good, good, good. I thought I was in the wrong market.
Anyways, but yes, their foundations are still exactly the same, focusing on building solid assets, making capital growth, working on building a passive income. All of those things are foundationally the same. The nuances that have changed are the things around
knowing that the ATO have more information available to them, so more data matching. So just making sure your clients are really clear about needing to report every source of income.
We're pretty lucky we don't have a large contingent of clients who are trying to get away with not reporting income and operating in the cash economy.
But I know a lot of accountants out there who have been shocked by some of the things that are coming through from the ATO now because they can Find out a lot more information than you think, even if you're investing in cryptocurrency. If you think ATO don't know about it, they absolutely do.
But also the advice around multiple structures.
So when I started, I don't know about your firm, Chris, but people used to have companies that sat on shelves, trusts that sat on shelves, ready to be given to a client when they wanted one straight off the bat so that they weren't trading out of brand new entities.
And every time someone did something new, you wanted a brand new entity set up to do that. And so it was quite typical for clients to end up with four, five, six, seven trusts. These days that happens sometimes for particular reasons, and there may be a valid reason to do that.
But there is a real tendency to keep things a little bit simpler for multiple reasons. Firstly, the ATO are inherently suspicious of people who have too many entities in play.
So one of their key risk profiling tools is having a look at how many entities you've got floating around there and saying, okay, why? What are we trying to do? What are we trying to shift? What's going on here? We assume there's something to be hidden.
Two, it costs you a lot of money. Even though the cost of setting up a trust or a company has come down a lot over the last 20 years, the cost to run them certainly hasn't.
And if you're going to do things like pay wages and all of that, that's become more and more complex over time. And thirdly, it's just confusing to everyone. The chance of that going wrong and the chance of a bank understanding your very convoluted series of 20 trusts. are significantly diminished.
If you've ever tried to get finance for a client who has a really, really complicated business structure that you from the outside look at and go, this is giving you absolutely no benefit.
And then they end up paying a really, really excessive interest rate because their risk rating with financial institutions is just through the roof. It's just, it's not an attractive proposition. So that's probably the one thing that's changed. We're keeping things a little bit simpler.
what's your thoughts on this um obviously with tax rates always changing right you know income tax company tax um you know and is there a movement towards maybe using companies more versus trust in the past or have you you know there's obviously changes with super in terms of limits and you know how is this sort of changing your you know for some clients who are getting close to you know these these limits
Yeah, so companies are great. The tax rates are fantastic. But those tax rates only apply while the money stays in the company. So companies were using quite extensively for trading entities. Back 20 years ago, you'd quite often trade your business out of a trust.
These days, because of tax rates, you tend to do that out of a company and retain some income. But property doesn't really work in companies unless you're doing development purely for sale because you don't have access to the capital gains tax discount when you're selling property in a company.
And even though that 25% tax rate is pretty close to the effective tax rate when you sell as an individual because you end up at 23 and a half by the time you sell. Apply your discount, even though they're fairly close.
When you take the money out of the company, you obviously pay the top up tax. So the loss of that capital gains tax discount means that's never a practical option for property investors, developers, different story. I mean, self-managed super is still something that is really popular and really popular amongst property investors.
But again, the cost to run them mean you have to sit down and do a pretty good cost-benefit analysis to make sure that if you are going into that space, you're actually doing better than you would be outside of the self-managed super fund space.
And getting some really sound financial advice from a licensed financial planner before you jump into something like that is really important. Yeah.
A couple of – we've noticed that there's a lot more recent resurgence of interest in the SMSF space in terms of buying property. And we've talked about it before on the podcast. I know, Chris, you've said that you feel like this is in part driven by buyer's agents, which is a bit sad.
And I know there's a lot of –
You know, people in the property space and the mortgage-breaking space, for that matter, at the moment seem to have their beady little eyes, their greedy beady little eyes on people's super balances saying, you can, you can buy it.
And because we, as a culture, we tend to love the idea of investing in property, we trust property values. Rightly or wrongly, more than we trust this sort of invisible nebulous sort of super structure or super industry, you know, we're sitting ducks in many cases.
And one thing I discovered fairly recently actually is a courtesy of the Investopoly podcast. I don't know if you listen to that, Catherine, but Stuart Williams is a regular guest on the podcast.
And, you know, that you need to have liquidity in your super fund because you get to a certain age, you need to start drawing down. And if you don't have enough cash or, you know, share portfolio or whatever that you can liquidate, then you're going to be forced to sell the property.
And I honestly, I'm a property person and I've only in recent years discovered, maybe even in the last year discovered that. Yeah. And I didn't know that. And now it's an absolute reason why you need to go and get specialist advice.
Don't listen to a buyer's agent who's trying to encourage you or a mortgage breaker, for that matter, is trying to encourage you to buy a property in your super. But can you talk to that and explain why that's an issue? And I guess who's most vulnerable to that issue?
Yeah, absolutely. And I can tell you from my experience on Instagram, it's not just buyers agents, but there's a bunch of Instagram influencers out there spruiking setting up self-managed super funds for people with balances as low as $150,000. Oh my God.
Which is just not what you need in order to make those cost benefit analysis stack up. But your friend of the podcast is absolutely right. That liquidity event when you need to start drawing a pension is needing the liquidity and being forced to sell.
Again, we're left with another situation where you're forced to sell a property that is not at a time of your choosing and it's not likely to be the right time. So we don't want to get ourselves into those positions. I personally own property in a self-married super fund, so I'm not against it.
It can work really well, but I've got a really long time till I need to retire and And I have the cost benefit stuff all worked out. So it's not that it is a terrible, terrible idea. We've seen people do really well out of it.
But if you're being told to do a purchase of an investment property in a self-managed super fund by someone who's not a financial planner, they're making money from that transaction. They're not advising you on that because it's in your best interest.
They're advising you that because of the commission check that is attached to it. And that might be the only way that you can borrow. But some of the drawbacks of buying investment property in self-managed super in case you're not familiar with them, the lending requirements within super are different.
So we can't rely on equity or do any of those things. We have to fund the deposit. and the stamp duty. Generally, the lending amounts are less. So most of the time, they're only going up to 70% of the value of a residential property.
So you're funding the 30% deposit plus the stamp duty in order to get into those loans. And we're not able to do things like rely on that equity in the future to make additional self-managed super fund purchases.
The interest rates on the self-managed super fund loans tend to be at least 1% more than the interest rates outside of the self-managed super sector. So, you know, making those dynamics about the return get a little bit more challenging with those additional interest rates.
You're restricted about the types of things that you can do. You can't necessarily borrow to renovate the property down the track or do any of those sorts of things. You certainly can't have any family members or friends living in your property.
You definitely can't buy a holiday house in your self-managed super fund, seeing that one too many times.
And as you say, the exit provisions with some of the capital gains tax concessions in super can be fantastic, but only if you can fund your pension payments and things until you're ready to sell a property.
And you don't want to have necessarily all of your super fund assets tied up in one asset. And the ATO has started asking on the self-managed super fund tax return form for details around self-managed super funds that have a single asset.
Because one of your requirements, along with maintaining the liquidity of the fund, is also taking consideration of the diversification of the fund. Because we know some diversification mitigates some of the risk associated with investment. So there's a lot to be considered and not to be disregarded as well.
The administration required to run a self-managed super fund is significantly more burdensome than having your super in a normal super fund. And for some people, that's a bridge too far.
If you're late with your super fund tax return, it's not a slap on the wrist like it is sometimes when you do your personal tax return a little bit late. Your super fund can't take contributions. It can't make pension payments. It can't do anything like that. until it's up to date and complying.
And if you get things really, really wrong, they can impose penalty tax on your entire fund. So it's just not to be taken lightly and certainly not something that you want to buy from a salesperson. You need to get some professional advice.
is the main reason for all of those sort of rules because it is such a great tax environment. I mean, what, you're paying 15% tax on contributions, right?
And then obviously down the track you get income from that and you don't pay any tax on it and there's lots of those sorts of benefits. And so... I'm guessing that the ATO is very protective of the fact that it's such an advantageous little environment.
The other thing too is, of course, that your tax deductions on that higher interest cost is smaller because you're only paying 15% tax in your super as well. So the benefit, I came across, I had a client who before she came to us, she was in her 50s.
She'd been sold up the river, you know, Spruka got hold of her, one of those one-stop shops.
They didn't have any accountants in the one-stop shop, amazingly enough, but they had enough people to sell her this dream of buying a brand new house and land package in her super fund at the point which, you know, she didn't realize it would basically take her entire balance to fund the deposit and the costs to set it up.
She didn't realize that she's not getting the maximum tax deductions because of all the depreciation because it's only 15% tax. She didn't realize she's less than 10 years away from when she wants to retire that she's going to have no cash. She's going to have to sell it. You know what I mean?
She just didn't know any of this stuff was not advised to her and yet it was allowed to happen.
So there's all these rules in play, but there are lots of bad actors out there that are very, very happy to grab people's balances and hoodwink them and bamboozle them effectively because she'd never considered any of this stuff and didn't know any of it until after.
Yeah. And these days there are places you can report those things too. So if you do find someone really trying to spruik you a self-managed super fund that's inappropriate, there are avenues through ASIC that you can complain. But unfortunately, that's not an isolated incident. People do sorts of things.
When we get to our Dumbo story, I've got some pretty big horror stories when it comes to the setup process of a self-managed super fund and some of the more obscure things that
that a financial planner will consider for you, but that most people wouldn't consider when they're reviewing getting out of your self-managed super fund. But it is pretty horrible. And it just emphasizes the importance of getting professional advice. And to be fair, that advice shouldn't be coming from an accountant.
That's not to come from me. That needs to come from a licensed financial planner. At the end of the day, your considerations around self-managed super funds go well beyond tax. Yeah. Yeah.
Where do people go wrong with their owner-occupier? I can see people renting out Airbnbs and that looks so great. Rent out the place for four weeks over summer and go rent somewhere else.
Is there some other ways that you see owner-occupiers still get their tax situation wrong where they don't think about negative consequences of certain things?
Yeah, absolutely. So the Airbnb one that people typically get the most wrong is just not understanding the difference between that temporary absence rule that we touched on with the six years before.
So, you know, if you temporarily vacate your property for capital gains tax purposes, we can still treat it as our main residence. So if you want to go just travel around Europe for three months and rent your home out for three months only, On Airbnb, we've got no issue with capital gains tax.
Assuming you move back in, you don't cease being a resident of Australia for tax purposes, all of those things. But if you rent out part of your home, so let's say you've got your main dwelling and out the back you have a granny flat that has separate access and all of those things.
So it's a great little avenue for income. That can be a wonderful thing. But it does have capital gains tax consequences. There is no six-year temporary absence rule for you living in your main dwelling and renting out part of your home. We have a proportionate capital gain.
And because human nature is you try to apply logic to tax, don't try to apply logic to tax. You can't do that. That's not how it works. There's just a set of rules.
So if you rent out part of your home for the whole time you live there, that part of the home is going to be subject to capital gains tax when you sell it. And there's a calculation to be done.
We have to apportion the cost base based on a fair, reasonable basis and do a range of other things. But that can be one that people typically, again, not necessarily a bad thing.
If you've earned some great rental income, it's helped you get out of debt quicker and all those sorts of things, that's fine. But it's just that sting when you get an unexpected capital gain, something you were expecting to be capital gains tax-free.
And I would imagine that the record-keeping in the meantime would become quite onerous.
If it's Airbnb, for example, it's not going to be renting the granny flat out for a continuous period of time where you'd be able to get all your property management statements and keep them in a shoebox and time comes, there they all are.
I mean, you've got to actually be working out, you know, how many days of the year I guess it's occupied versus unoccupied. Like, it would become quite challenging, I would imagine. And... How many people know that they have to do that?
Well, I guess, yeah, when it's available for rent versus not available for rent as well. But, I mean, most people don't necessarily know. But if you've got a good account, they're going to ask for that information when they're preparing your annual tax return.
There are reports that you can get from Airbnb that supply that information. So that's something that we would readily ask for during tax preparation. And please no shoeboxes. Ideally, you've got a record keeping system that is slightly more sophisticated than that, particularly if you're becoming a property investor.
You don't have to keep original physical copies of your receipts. You can scan them. You sort them in a folder on your computer in chronological order, something like that. But you do need to keep those records.
Because if you don't and we can't establish your cost base well when you sell a property, again, undoubtedly, you're paying more tax than you need to.
Absolutely.
Well, here's a hack for that. I mean, you know, I've done this myself and certainly in my property management business. We encourage our clients to do this and that is get your property manager. This is not the Airbnb thing, of course, but get your property manager to pay all your bills.
And then it's all captured in one statement. It's a very efficient way of… of managing that part of it.
Catherine, you mentioned the Dumbo. And we're keen to hear your Dumbo story. So hit us with it.
What's a lesson we can learn from your story? So to be clear, for the purpose of this story, the Dumbo are the professionals involved in this scenario, not the individual clients because they are not to know the intricacies of tax law and superannuation.
But we had a client many, many years ago, before all of the changes around the accountant's exemption for setting up self-managed super funds and all of those sorts of things, who
who, like you've suggested, not a buyer's agent but a property developer, encouraged to get into the self-managed super fund space and said, okay, set this self-managed super fund up, roll all of your super into that fund and then purchase this property. And they did that.
But when we went to do the self-managed super fund tax return, so they set it up somewhere else and then brought it to us to do the tax return,
We discovered that that client was in a particular type of fund called a defined benefit fund, which is a very lucrative superannuation option that is just not available anymore.
Public sector employees many years ago used to get them, but they are one of some of the best superannuation products you can possibly be in. And rolling out of that
product and you can't get back into them cost him literally hundreds of thousands of dollars so part of the reason you go to a financial I've got another story that goes along with this part of the reason you're going to a financial advisor about that self-managed super fund set up is not about what you want to invest in it's about what you're exiting what are you giving up and
And on that note, just recently, we had a new client approach us about looking after a self-managed super fund that they'd already set up. And unfortunately, that client had been quite sick and had cancer.
And they were diagnosed with cancer only a couple of months after setting up their self-managed super fund, which again, they did not get proper advice about. And they rolled all of their super funds at the instruction of a professional who is obviously got pretty poor ethics, or
all of their super funds into the self-managed super fund from their existing super fund. And guess where their insurance policies had been to cover them for things like critical illness and cancer. It was in their super fund.
So by rolling all of their super fund into the self-managed, they lost all of their insurance coverage and had to go through that cancer journey with nothing. No support. Yeah. So the financial advice process is not so much about their property investment.
And I think sometimes the accountants can get a bad rap for being the negative Nellies and trying to quash your investment dreams. But it's about making sure that you have taken into consideration all of the circumstances around the self-managed super fund, not just what it is you're trying to buy. Yep.
Oh, that's sobering, that example. And I have heard some similar stories. And yeah, back to that sort of the insurance, just that little thing that everyone seems to forget. It's part of their superannuation fund.
And in the excitement of being able to invest in property and I know that some people invest in property in their super fund because they can't actually afford to invest in it outside of it and they feel like they're missing out on something. So it's like their way to join the party.
And it's terribly tragic, actually, when it ultimately costs them.
I mean, a financial planner actually referred me, a client to me some years ago, it was a new client of hers, who, for a strategy session, and they had sunk, and they were in their 50s, and they'd sunk their entire superannuation balance into two apartments in Townsville.
Um, and look, this was some years back and they were, I mean, I'm trying to pluck the figures out of their head, um, it was something like they purchased price of like 350,000 at that point, some, some seven years afterwards, they were worth 250,000 each.
And, and effectively what they then lost was what their original balance was before they went into the exercise. So they'd wiped the, their cash balance of the super fund out. By capital losses. So they ended up with nothing in the super. They ultimately had to sell.
They had no choice. Basically, when they went into retirement, they had to get out of those properties anyway. And they just had to take a bath, which is just appalling. It was the first time I'd come across such a terrible situation. And I know since then I've come across many, many more.
So, yeah, it's awful. Ending the episode on a pretty down note. So I think sort of if we put some positivity back into this, this is really about this whole podcast. We want to encourage people to make good decisions.
And if you don't know what the risks are, then often we take those risks completely unknowing. So, look, Catherine, thanks so much for sharing this all these stories, all this knowledge with us. And we'll put the link in the show notes if anybody wants to reach out to your business.
And you've come on, you've done a couple of things with me and my various activities. And I've really appreciated your depth of knowledge and your clarity with which you can explain quite complicated concepts. So thank you so much. Thank you so much for having me.
And thank you for taking the time to listen.
Great to meet you. Thank you. If you have a question that you'd like us to answer in an upcoming Q&A episode, you can send us a voicemail or written question via the website, theelephantintheroom.com.au, or you can email us directly at questions at theelephantintheroom.com.au.
If you like what you're hearing, please share this episode with others you feel would benefit. And while you're at it, why not leave us an iTunes review? Five stars would be great.
I know that sounds a bit cringy, but we have it on good authority that every review helps make it easier for other people to find out about us and hear what our amazing guests have to say.
Key takeaways
- The conversation with an accountant belongs before the purchase, because there are no tricks available afterwards on stamp duty or ownership structure.
- Trusts suit some buyers, but for a typical high-salary employee chasing negative gearing they can add thousands in land tax for no benefit.
- The quickest way to lose money on property is being forced to sell at a time you did not choose, including inside a super fund.
- On a former home, the cost base can be the market value the first time it earned rent, not the price paid, which changes the sums entirely.
- Every dollar of depreciation claimed comes off the cost base, so the sting arrives at sale rather than during ownership.
- Financial advice on a self-managed super fund is as much about what is being exited, including insurance cover, as what is being bought.
When Should You Get Property Tax Advice?
Catherine Simons is the managing director of WSC Group, and she came to property through the tax return rather than the other way around. She started at 18 preparing investor returns for people on moderate incomes and for very wealthy clients alike. Nearly 20 years on, she says she still learns something every month.
On timing she is blunt. At 12:15 she says that if you are not having a conversation pre-purchase, there is not a lot that can be done afterwards, and that she has no tricks relating to stamp duty. Even in her own client base, those who arrive after buying outweigh those who come before, partly because so many investors are accidental landlords.
For a client who comes early the work is not exotic: what they plan to do over the next 10 to 15 years, and when they might sell.
Should You Buy Property in a Trust?
Barely a day passes without a client asking Simons whether to buy in a trust. She owns one and rates them for the right person, but they cost more to run than owning in your own name. A typical employee on a high salary chasing negative gearing gets no favours from a discretionary trust, and depending on where the property sits, may pay thousands in extra land tax each year for the privilege.
Chris Bates raised a client from that morning: an anaesthetist on close to a million dollars, low debt and real exposure to being sued. Simons' answer turned on employment. Someone in private practice employing others may already have a structure that emulates the negative gearing position. It is the ordinary employee for whom a trust becomes costly overkill.
The same restraint shows in entity counts. Clients once ended up with five, six or seven trusts. The ATO now reads a pile of entities as a risk signal, running costs remain high, and lenders that cannot follow a structure sometimes price it dearly.
Why Do Investors Lose Money on Property?
Property is a long-term investment, and the best way to lose money on a property investment is to buy one that you are forced to sell.
Catherine Simons, 4:14
Australians can live in a bubble where nobody loses money on property, she says, and you might hide a loss from friends but not from your accountant. The mechanics are mundane. Transacting is expensive once stamp duty, reports and an agent's fee are counted. A forced sale can also stack a capital gain onto an already high income, where deferring into retirement years might have met a lower rate.
Borrowing structure carries the same quiet risk. Veronica Morgan described tipping the proceeds of one sale into a redraw rather than an offset account, and knowing in hindsight that she left money on the table. Simons frames the alternative as flexibility: where the property is not a forever home, cash held in an offset stays available for the next deposit without costing deductibility on the loan.
What Cost Base Applies to a Former Home?
The six-year rule generates plenty of errors. The one Simons singles out is not checking what a former home was worth the first time it earned rent, because under the market value substitution rule that figure, not the purchase price, can become the cost base. She walked through a scenario where the numbers reverse the obvious answer.
| Element | Figure As Stated |
|---|---|
| Purchase price of first home | $700,000 |
| Value when first rented, used as cost base | $1,000,000 |
| Sale price after five years rented | $1,100,000 |
| Capital gain on that basis | $100,000 |
| Taxed after the 50% discount | $50,000 |
| Growth in the newer home over the period | $500,000 |
Scenario as described at 17:35 to 18:16. Figures as stated on air.
Her conclusion there is to take the hit on the smaller gain and keep the exemption for the home that grew more. Depreciation runs on the same delay. Every dollar claimed comes off the cost base at sale. It is usually still worth claiming, since the deduction is a full dollar now and only half returns through a discounted gain, but she calls it a sting.
We encourage people to focus on purchasing the best asset that they can afford and that they can afford to hold long term, rather than focusing too much on the tax, and let us worry about the tax.
Catherine Simons, 24:02
Who helps choose that asset is a separate question, because property investment advice in Australia sits outside the licensing rules that cover other financial advice, as Peter Koulizos has traced.
Can You Buy Property in an SMSF?
Interest in buying property inside a self-managed super fund has resurged, and not only from buyer's agents. Simons sees Instagram accounts spruiking funds for balances as low as $150,000, too little for the cost benefit sums to stack up.
| Element | How It Works Inside The Fund |
|---|---|
| Deposit and stamp duty | Funded by the fund; existing equity cannot be relied on |
| Typical maximum loan | 70% of a residential property's value |
| Interest rate | At least 1% above rates outside the sector |
| Borrowing to renovate later | Not necessarily available |
| Who may live there | Not family or friends, and not a holiday house |
| Tax rate inside the fund | 15%, which shrinks the value of deductions |
| Late fund tax return | No contributions or pension payments until compliant |
Rules as described at 39:32 to 42:43. Figures as stated on air.
The failure she keeps meeting is liquidity. A fund heavy in one property, approaching the age when a pension must be paid, has nothing to draw on and sells at a time not of its choosing. The ATO now asks about single-asset funds on the fund return, since diversification is a trustee duty.
Part of the reason you're going to a financial adviser about that self-managed super fund setup is not about what you want to invest in, it's about what you're exiting. What are you giving up?
Catherine Simons, 49:58
Her Dumbo stories make that concrete, and the Dumbos are the professionals rather than the clients. One client was moved out of a defined benefit fund he could never rejoin, at a cost of hundreds of thousands. Another rolled their super over, lost the insurance it held, and faced cancer with no cover.
Thinking About Your Next Investment Purchase?
Ownership and borrowing structure are hard to change once a property has settled, so the order of the conversations matters. Alcove works on the finance half of that order, including how an investment property loan is set up before the structure is locked in.
Investment Property Mortgage BrokerSources referenced: The Elephant in the Room, episode 371, "The Critical Role of Tax Planning in Property Wealth Building", released 9 February 2025. Host: Chris Bates (Alcove). Guest: Catherine Simons, Managing Director, WSC Group. Figures are quoted as stated on air and have not been re-checked against current data.
Press play on these