Curious about upgrading?
Wondering where to start?
Complex questions that need answers?
Is there a better structure for you?
"They managed to navigate my complex expat income and even got my Google RSU income approved as well."
"I highly recommend Alcove to anyone looking for a mortgage broker who is responsive, trustworthy, and truly cares about their clients. Thanks again to the whole team for making the process such a positive experience!"
"As founders, we're constantly jumping between things so having a partner that handled the details & made the process super clear made the buying process breezy for us. Very happy with the experience!"
“It almost felt like it was his responsibility to make it clear to me, not my responsibility to understand it.”
“I've been pretty much fully leveraged the whole time. So the sounding board on that, in terms of what was achievable, what wasn't — I think trust is just built along that.”
"Alcove has been a great partner. They look after my audience properly, keep things simple, and deliver real value. I’ve got full confidence referring clients knowing they’ll get honest, straightforward advice."
"Property is one of the biggest financial decisions people make. Alcove stood out because they take a strategic approach to lending - helping clients structure property and debt decisions in a way that genuinely supports their broader financial plans."
Adapted from audio. This article is a written adaptation of the original podcast episode. Sources and dates are shown with each figure.
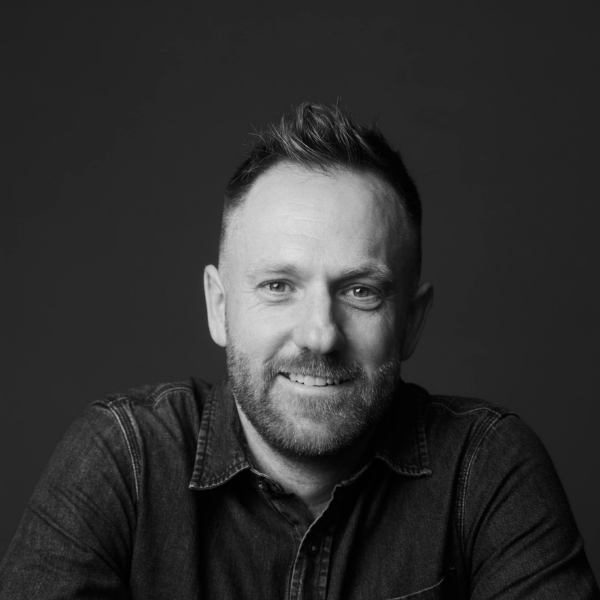

What Scott Aggett Learned From 23 Years On the Selling Side
Scott Aggett spent 23 years as a selling agent before he started negotiating for buyers. He tells Chris Bates what that vantage point shows about off market claims, wait lists and hotspot investing.
No one ever talks about motivation of the sales agent. Are they transactional? Are they going to fight for their vendor's position? And with that set of information, it then understands what paths are available for me to go down, what lines I can use to put pressure on them.
So understanding those three pillars really sets me up for the start of a negotiation because they're doing it to you in real time. And if you don't realize that's happening, you're stupid. Our motto is buy without regrets. And so...
If you can buy a property that will serve you for 10 years as opposed to three years, that will serve you well. Buying a great property today, that's not just what it's about.
It's also getting something that could be ripe for improvement when the time is right for that investor or for the next buyer. You think about, right, lifestyle, what's important to you? How do you get to work? What do you need for your family? What amenities like parks and shops?
Then you look at the budget.
Welcome to Street Secrets. I'm Chris Bates and my mortgage broadcast is 2013.
And in this podcast, we're going to be interviewing Australia's leading buyer's agents, ones with decades of experience, have the local insider knowledge on the street, and can really help you with your buying process, no matter whether you're a first home buyer, upgrade or investor.
In this podcast, you'll get access to Australia's leading buyer's agents' minds every week on a Thursday. What's the word on the street?
Welcome to Street Secrets. I'm Chris Bakes. Thanks for joining us today. Different episode today. I've got Scott Agate in the studio. How are you doing, Scott?
G'day, Chris. I'm well, thanks, mate.
So for people watching or following along at home, we've done a lot of sort of episodes around sort of individual pockets of capital cities and some regional locations now and really try to highlight the real experienced buyers agents that have really owned that pocket and have been doing it for sort of five, ten years, right?
And if you go back and look at all our episodes that we've done, We're going a bit of a different option today. I mean, I've got Scott Agate in today. One, because he did have a different buyer's agency type of service, which is the old company, which is around negotiation.
And it was a huge value add, I think, within the property journey. He has now got a buyer's agency that also does a lot of investing focus. In today's episode, we're going to unpack a bit of the challenges of the sort of borderless investment buyer's agent, what's sort of happening in the industry.
But I think Scott's a really informed view into this. So thanks so much for coming on.
My pleasure. Thanks for having me.
Scott, I mean, I kind of gave a little bit too much away in the intro, but can you maybe just give us a bit of a rundown of when you sort of got into the broader real estate
industry and just your length of experience and what made you sort of not only start Hello House, but then also do Green Shoots?
Sure. Well, the top line one for me is I've been at it for over 30 years, 23 years as a leading real estate agent in Sydney and London. So in Sydney, I formed the first three Bell property franchises in the eastern suburbs. I sold out of that.
Because I saw the rise of the buyer's agents in Australia and I felt there was as much smoke and mirrors on the buyer's agent side as there was on the real estate agent side. And what I saw was the problem with buyers that had no idea how to analyze property.
They were really emotionally connected to the homes that they were chasing and they were overpaying in the negotiation, especially at the hands of an agent or at the hands of an inexperienced or bad moral compass buyer's agent who was very transactional.
So I built a global first negotiation as a service business called Hello House, did that for seven years, focused on predominantly owner occupiers, but 25% investors that had the capacity to find their own properties before they handed over to us nationwide to do really accurate due diligence analysis and then control the negotiation.
That business was acquired by Listing Loop and then subsequently acquired by Lendi and Aussie Home Loans. And then I wanted to do something exciting in the investor space.
They're aligned with how I personally invested over the years as well, which was using data to get ahead of the herd and buy ideally six to 18 months ahead of the mass market and really focus on early growth stage property.
All right, we'll go into a bit of detail on that, but I do think your experience is quite unique. I mean, there's obviously a lot of buyer's agent that have tried to be a real estate agent and a failed real estate agent. I'm just being honest.
And they rebrand themselves and they go on the buyer side. And I don't think that sort of sales mentality is the right thing. I mean, because you sort of did climb that sort of real estate world and you were actually running a principal and you're running multiple offices and
You had that real sort of experience. You became one of the top real estate agents, I guess, in a lot of sense and became more of a trusted advisor. Does that then allow you to jump a lot of steps when you're going to that negotiation?
You were just thinking about things a lot more on an advice side than a sales side?
Yeah, I was pretty analytical in terms of breaking down the buying process and the nuances in negotiation and looking at the psychology of it from both the agent side, the buyer side, the buyer's agent side, and having that depth of experience allowed me to pull that out.
that process apart and then really try to understand where the opportunity was to better it. I was an award-winning agent at Bell Property for the time that I was there, but I was never sort of absolute top tier.
And I think part of the reason for that was I struggled in the lying space. I wasn't comfortable lying to the vendors to win the listings, lying to the buyers to create competition and value for them to drive them to my auctions.
And I wasn't prepared to go in and do what my colleagues would, which is dial for dollars in their words. And I found that really unattractive in terms of coming in and just really calling people for leads and for listings. So I was very good at cherry picking.
And by that, I understood what the buyers were looking for very specifically, and then I would match them really well with properties. And I think that's what serves you well as a buyer's agent later on, plus the deep level experience from the agent side.
And yeah, 23 years doing that and over 4,000 property transactions gives you a lot of Shots at goal, Chris.
Lots of learning experiences and the beauty about being an agent, which is what I constantly say to people that want to work with me, is that I'll only work with you as a buyer's agent if you've been a licensed real estate agent before.
And the reason why is because when you're a buyer's agent, you get one go at the negotiation and you don't understand what's happening on the other side. When you're a real estate agent, you're negotiating against five, 10, 20 different people during that campaign.
You've just got such a great depth of data points and you just learn so much faster about the nuance of negotiation.
Yeah, so you've got a big believer in buyers agents that have come from selling backgrounds, got a huge advantage of really understanding the deep motivations of vendors, but also how a lot of other buyers are sort of negotiating.
Is that one of the biggest insights you get over other buyers agents who have come from a legal or whatever it might be background?
I find it shocking, Chris, that you can be a licensed buyer's agent or you can be an award-winning buyer's agent and only have ever acted on one side of the process and you have no idea what's happening to you in real time.
So I don't care if you bought five properties or 300 properties. If you've never sat on the other side of the fence, you don't know how the full process works. And I think that you're therefore practicing on other people's money.
And that's where it becomes really transactional because people aren't fighting to save the maximum amount of money they can in a deal. They aren't too worried about analyzing property to an nth degree because it's all about just getting the deal across the line. It's a different mindset.
So we're tracking our accountability based on how accurate our analysis is versus what our clients pay. We'll price things to a $5,000 increment. We do it manually. We track that every month to see what the variance on that has been.
We can quantify how much our clients save money in the negotiation based on the target price they set us.
These are important metrics, but I think you only put that level of importance in it if you sat on the other side of the fence and you understand why that's important, why people are paying a premium or why they're paying fair market value.
Obviously, you understand their game. You can sort of cut to the chase. Mate, I've been on your side of the fence. I'm sure there's an unfair advantage you maybe have over other buyer's agents sometimes where you can
of cut to the chase to the agent and you can sort of build that rapport a lot deeper than say someone who's never sat in their shoes yeah you've walked the walk i can use the language that they use and i use that language in reverse to circumnavigate the to give my client an advantage as well or find a path forward that they might have not otherwise found themselves to another buyer's agency or if they were going it alone so i think there's a lot of advantages in in terms of that deep level of experience coming from from the the agent side
which is actually why I was a good financial advisor in terms of I could really unpick deeply what clients wanted. I could ask them really deep questions. I challenged their thinking.
What I found really hard is sort of not telling them the good stuff until they paid me a $5,000 fee and holding it back. I just wanted to help. And a lot of great advice is actually quite simple advice as well. And they don't need these big complex plans.
So it's one of those things I found hard to monetize as a financial advisor. In fairness, as a broker, we don't have to worry about that.
You mentioned that the uncomfortableness around lying and playing the game and not just having to do it with the vendors, having to do it with buyers as an agent. It's two way there and lots of buyers as well.
Do you not have to do that, though, a little bit as a buyer's agent, as a negotiator as well? Have you found that you've been able to still get the negotiation because you kind of do it on facts rather than the client's position a little bit more?
Or how do you do it? Well, the thing that I say to the clients all the time is transparency starts with me, right? So we have to be completely transparent in our inner workings about how we arrived at a particular number.
We've got to give our clients a lot of confidence to act on the basis of that. And then we can show them and we can quantify, as I said, the amount of savings and how hard we're working.
And the fact we're tracking those results and I've done that for a decade is, I think, really important and shows that level of accountability from our perspective. No, I certainly don't think you need to lie. I think it's the opposite. You need to be a really clear communicator with your clients.
The thing that I've instilled in my teams that I've worked with that whole time at Hello House and at Green Shoots is that you've got to get to the client before they get to you. It's my favorite thing that I say. My team is sick of hearing it.
But I think it's really important that you highlight all of the potential red flags or the issues with the property or with price. You address those. You come to the customer with not only those red flags, but come with solutions of how you can navigate around that to get them the result.
Or you walk away from a deal and you communicate really clearly why you're walking away from that deal. There's no value in it or there's a problem with the property. that you're not comfortable with.
So I think, again, this is another thing that if you've been in sales for a long time, where you've got a good moral compass, that clear communication can still get you fantastic results without actually having to sit there and lie to your customers to get deals done.
wasn't the angle i was going on the question but it was a good answer um and it did highlight you know some really good points there which i do value i value that one who can you know have the difficult conversations early highlight issues you know talk about the negatives more than even the positives and sort of be up front with the client fully transparent i think when you then flip it then you've got to act in for them on the negotiation maybe because you sometimes got to play the smoke and mirrors and give the agent the story how do you sort of
Sort of then also, I mean, cause you are protecting, you're acting for the client. That's one of the best thing about buyer's agency. I feel is that you've got a set client you're acting for.
You're not acting for many parties and your job's to, to work with that client and they're paying you a fee for that.
And you can be honest and upfront with them, but with the agents, is it, do you just have to play that game sometimes as part of the negotiation or are you just, Much better now.
Yeah, definitely. I'm having to use those life learnings from sitting in that other seat to use those lines in reverse and use those to find pressure points. So really the thing for me when I go into a negotiation is less about comparable sales.
For example, it's more about the psychology of it, like understanding and determining the vendor's motivation, understanding the buyer competition that I've got. And this is a really important one that no one ever talks about. Understanding the motivation of the sales agent. Are they transactional? Are they going to fight for their vendor's position?
And with that set of information, it then understands what paths are available for me to go down, what lines I can use to put pressure on them, how I introduce time pressure into the conversation as well, and can leverage other properties, for example, in terms of competition.
So understanding those three pillars really sets me up for the start of a negotiation. But yes, I have to play games with the agents all the time because they're doing it to you in real time. And if you don't realize that's happening, you're stupid.
Yeah, I think a lot of clients do realize that when it's too late and they've just, the one that got away is the one that they got to the point they did want it. And then all of a sudden they got lost in the negotiation game.
And then they realize very quickly after that is, oh, they don't really know what they're doing. And sometimes they don't learn on the first time. It's multiple times, right? Yeah. Yeah.
It's hard. I had a client recently that we just bought from the Gold Coast. She engaged me. They'd been looking for about three to six months themselves. They're working with us for say two weeks. They found the dream property they wanted.
And then she wrote me an email and said, Scott, I've paid you, so I want you and the guys to do the analysis and negotiation. But I actually feel bad because this is the best agent that we've dealt with the entire time through the process.
He's made it really easy for us and he's told us we've just got to put 1.35 on the table and he'll very happily get it closed with the seller.
So I feel bad because we don't really need you and we've overpaid in this process by employing you because there's not really any value you can add here. This isn't a humble brag. This is just a really good insight into where you were leading me just then.
Two minute phone call, establish those three things, save them $25,000 because I could establish there was no other buyer competition. I baited the agent at a lower price. He bit. straight away and I realized that we could save some money.
So even the buyers with their perception that it's going to be simple because the agents, you know, a good communicator can build rapport with them, are getting the wool pulled over their eyes.
So the statistics that we kind of looked at over the last, say, 10 years is that for every million dollars you're spending in Australia, the average buyer is overpaying by $50,000. And that's overpaying the negotiation,
overpaying for the reference that you just said then of missing properties that they're spending money on, building and pest reports, contract reviews, and their own time.
The average customer takes 10.1 months to close a deal in Australia versus if you're using a good buyer's agent, our team on average close in three to six weeks. Time's not the factor why you should use a buyer's agent in that regard, whether it's two weeks or two months is irrelevant to me.
It's about right property, right price and right fit for the client. But there is a significant time-saving cost going into the loan when you are practicing and you don't understand what's happening in real time.
And just putting it out there, some buyer's agents will do this and some buyer's agents won't. Some will have like a negotiation service and their local specialist, and some won't want to do that.
They'll only want to do full service or a part, or they'll want to go deep on a property review rather than just offering a negotiation. And so those services do sort of sometimes exist, but then you've got to find the right buyers, you've got to build rapport.
And so there was a real place for sort of Hello House. I think let's go on to the next topic, which whenever I sort of get someone on the podcast because I do rate their service and I do rate them as their value proposition and most likely we also work with them.
So when we talk about this sort of borderless bias, we haven't worked with Scott as a business around referring in clients for this service. However, We're going to go deep around some of the challenges.
And this is also the challenges we have as a business, finding people to work in the investment space for our clients. When you sort of look at it, right, you've sort of pivoted a little bit from a negotiation only service into an investment focused sort of borderless sort of buyers Asia.
And when you look at it just like on a white piece of paper, what are some of the challenges of that model that you've seen when you've observed a lot of other businesses in this space?
Well, a lot of it is the same references that we've just been talking about. I look at the incoming sheer volume of people that are in the industry or new to the industry that are very good marketers, but don't come with any industry experience.
So whilst I was addressing the owner occupiers who would otherwise be going it alone when I built Hello House, it's exactly the same for the investors that were going it alone. So there was an opportunity to work with customers in that vein.
And then I just saw the opportunity in terms of those that are using a buyer's agent, a full service buyer's agent, because it is a real quandary for this point that you've just discussed. And I've had these debates with lots of buyer's agents across the country in a friendly manner over multiple years.
Like, do you go to a local expert or who is going to talk all things around the reasons why you should invest where they locally live and breathe?
Or can you go to someone that has a unbiased view nationwide that can match that up with your risk profile, your financial goals, your budget, your financial cashflow requirements? I think it's the latter for me that is the right option. You know, You could debate it either way.
I'm sure you've done it a lot over the years as well, whether there's a right or wrong answer. The challenge is if you go to the local agency, you're definitely going to get better on the ground intel than using someone that's nationwide.
However, you're going to get very biased opinions, I think, as to where you should invest. So it's almost like And I've seen some people talking about this in the industry that you need to have a independent strategist at the top that comes through from financial planning or their broker.
They see someone independently that's just working on the strategy piece and the suburb selection, and then they appoint someone locally on the ground that can execute on that. That model in theory would be great. My understanding at the moment is it doesn't exist.
And you've got to retrain an entire public or industry as to the value of that service, which is going to be a challenge for anyone to get that off the ground and do it.
So I think we do the best that we possibly can, being able to offer alternative options to give people a diversified view of how they can balance their portfolio and what's the right fit for them.
One of the issues in property is people go and speak to a broker or they speak to a financial advisor. If they go to an advisor, advisors really generally don't have much idea around property.
They've in the past been very anti-property, put my money in super by shares, et cetera, and they're not trained on it, they're not licensed on it. And so there's a huge gap with more property advice within the advice world. Then you go into the broking world and it's kind of similar, right?
They understand mortgages and they're not focused on trying to make sure the clients get great outcomes from a property point of view. And so they just sort of facilitate and validate rather than step up to this trusted advisor and helping the client really think it through.
Or what they'll do is sort of partner with one organization that will, they'll just send all their clients through, either it's owner occupiers, et cetera. I mean, there has been an explosion in buyer's agents that sometimes they bring it all in house. So the advisor,
with the broker and then have their own buyer's agency as well.
But unfortunately, from my experience, I find that that one stop shop really struggles because you've got wage bills, you've got KPIs, and you don't really get the top buyer's agents working in those firms because the reality is if they were, they'd start their own firm, same as the advisors and the brokers.
And so sometimes the quality advice, it can be sort of sales driven rather than client outcome driven. But you're right, this sort of property strategist thing, but it's hard because
know you need someone with a national like knowledge you'd need someone to be have the relationships with lots of different buyers agents all across the country but then when you get to this sort of borderless sort of buyers agent role you know it's really hard to scale buyers agency right scale you know across different states know all the different markets you know and have the team and i think a lot of different companies have tried this but
often they try to scale quite far. That's one of the issues you've seen is they've almost like it's a really hard job to scale, but they've scaled anyway.
I believe the biggest problem at the moment is these sort of top tier, if you will, profitable buyers agencies that are really focused on the sheer volume of numbers, which means they'll go into a market and mop up 50, 100 assets in a month where there's just not 50 or 100 assets worth buying.
That becomes cookie cutter advice. It then is a rush to do deals and you're therefore overpaying. You're at risk of cutting corners in terms of the quality of the asset.
So that's the feedback that we're getting in the industry a lot from clients that have worked with agencies of that size before that it becomes very much a number. There's a lot of tactics that we're hearing as well internally along the lines of, you know, You'll sign on.
You've got to join a very long wait list. They put you in a queue. You get to the top of that queue, but they deliberately wound down your 90 day pre-approval. You get to the top of the mountain and they say you're buying property X.
And if you don't say no, the threat is you go back to the start of the queue and go through the whole process again. So there's pressure tactics like that.
There's this bullshit statistic that we see constantly, which frustrates the hell out of me as an ex agent, which is 83% of my property is bought off market. And it's like, well, it defies logic for me. We do about 15% and have always done somewhere around 10 to 15% off market.
And that's because there will always be a small percentage of people that are motivated sellers. They're bored already and need to sell. They're under financial pressure. They're sick, they're inexperienced, whatever that might be that drives those outcomes. But there's certainly not 83%. There's certainly not 40%.
And the reason why, if you're an agent, and this is just absolutely clear as day to anyone that's sat in the agent chair, is if I'm going to market a property, I want my four weeks in the sun as an agent to build my profile, to do what's called list and last in the industry as a career earner.
If I'm going to have to sell that behind closed doors where I don't get a chance to meet any of the neighbours and promote that opportunity and to drive more listings and referrals, you're going to pay an emotional premium for that opportunity and you're going to do it with a cherry on top, right?
So any career agent that's selling off market is going to make you pay a premium for that. So anyone telling you that they buy all these properties off market is a giant furphy. It's the biggest furphy in the Australian real estate market for me. And unfortunately, it's used as a marketing hook.
you know, that's the power of listing with them is that you'll buy things off market, which for me is just equating to you guarantee that you're going to overspend.
Yeah, and then the other ones they use is I buy fast and I buy under market value, you know, just to find logic, right? And I use them as the number one marketing tools to attract clients to work with them because... you know, off market fast and under market.
I mean, what's what's wrong with that? Yeah, it's the holy trilogy. Yeah.
Yeah. Yeah. I mean, under market's an interesting one. I mean, if you pay the price, you know, it is market value, right? So you've said it. But I could argue that we buy under comparable sales evidence and we consistently do that, otherwise we'll walk away if we don't see value.
So there's an element of truth to that to some degree, but we don't use it as a marketing ploy either because it's deceptive, I think, in terms of it's misleading. The other thing is buying under bank valuation. We bought and we constantly do this.
If you use a CBA valuation, as you well know, then we buy everything under market value or under valuation by a long way. But that's a vanity metric as well. And we'll say that to our clients too.
We'll get a valuation done on it by CBA if you want it to understand potentially the equity that you might have built into this upfront if you meet the bank serviceability and you want to lend through CBA. But it's a vanity metric.
It's in place instead of them doing a $35 million advertising campaign on every bus stop around the country. They've loosened up their valuation tool. You could essentially use that if you want to go and do it, but you're going to be borrowing above what market value is because you've just set market value.
So we'll do all that work for the customer. We'll show them that, but we'll also fill them with the absolute truth of that's not a good metric in terms of how well you bought. Yeah, absolutely.
neither confirm or deny whether it's CBA or not, but there is absolutely a valuation. But what you absolutely say is absolutely correct. One of the other marketing they do is they use same messages to clients six months after they purchased. And I got a bank value and the bank value was much higher.
And look how well you done. The client doesn't understand that that bank value is highly optimistic and is in the bank's interest to be high because they want you to borrow more money, right? And they want you to leverage up further. It's not a conservative valuation in a lot of these cases.
These are actually really aggressive valuations that you wouldn't probably be able to sell it for. And have you really made money over six months when you've got cost to buy, cost to sell, buyer's agency costs, capital gains tax? It's too early to decide whether this is a good investment.
What you mentioned there around the scale and the order and the pressure testing, I have heard that, maybe not as clear as that in terms of how they're doing it. The reality is there's a competition on brief, right? Like A, the waiting queue. That doesn't make sense, right? Because that's an opportunity cost.
Why do I have to wait? Two, when I do, how do you decide which property goes to who? Why does that person get a better property than me? If I'm number seven in the queue and they're number six.
This competition of brief, it's an obvious conflict, but they seem to be able to just keep on pushing on through that. And as part of the pitch is we're there and we just are buying up everything. It's this sort of greater full theory.
Yeah. And beyond that as well, we're seeing a lot of pushing to really small regional markets and size has no relevance to capital growth. So there's some good markets that will perform really strongly or outperforming in capital city markets that have got very low population.
And it doesn't matter, as you know, whether you're in the coast or you're in the bush or in the desert, if all the supply demand metrics line up and lots of other filters that we would be looking at, then it could be a good place to invest.
But we're seeing sub-par locations that I can see in the data. We're seeing compromises on due diligence like flood and bushfire zones. and busy roads and roundabouts and these types of things that we wouldn't compromise on. And I think buyers that are inexperienced believe that they're paying for expert advice.
And I think they're getting pretty inexperienced people that are dealing on the whole with their hard earned money and they're gambling in the hundreds and hundreds of thousands of dollars. So it's a lot of risk in the industry. You need to really understand who you're investing with.
The other thing, Chris, that really scares me in the industry, this is a bigger picture, 10,000 foot view that I know you and I both been in and around the industry for a very long time, is that the padding on the back from the industry, from mortgage brokers, from financial planners, from other people, professional services,
clapping from the stands, patting these people on the back because they're building huge volume businesses. Yes, they're making lots of money. Yes, they're building huge portfolios for themselves. Yes, they've got lots of flash cars, but that's become the pinnacle.
That's the goal now for all these people is to have a business like that. So I find it a challenge just even in the industry to keep a low profile at this and win because you're competing against this marketing noise the whole time.
And unfortunately, that seems to be what resonates a lot with other industry professionals, which is scary because if you look below or under the bonnet, there's a lot of issues with scale at all costs.
Yeah, I mean, I do want to double down on the asset quality. I mean, we've seen it. We've seen clients gone to these buyers agents and they've come to us because they found out about us somehow. And then they go, we're looking at this or we've bought this.
And I say, well, who did you buy that through? And you're absolutely right. Just due to the scale that they're buying, they're making deal breakers that the locals would never want to make. Any experienced local property investor would never want to buy all those things you mentioned.
They're ignoring that the property has been on the market for two months. They're not buying because it's the easiest one to buy. And they're making huge mistakes. And they're just basically saying, well, the market's going up, the city's going up or the town's going up.
Or like you said, I don't think too many deserts are going up. But ultimately, your point is really smart there because it's absolutely what I think happens in these Because the buyer's just been doing it for a year or two. They haven't actually been they don't know that market.
They've probably never even been to that market. And they haven't even looked at the property. And so buying completely sight unseen. You've actually hit a nail on the head as well. But it's sort of like personal accountability. They're sort of following the people that are putting out the image of success.
Like you say, the cars and their portfolios and how well they've done out of property portfolio and why you should work with me is because I've got 20 properties, but
What they don't realize is most of it's BS. It's not true. They haven't actually got the portfolios size they're doing their personal stuff.
They're often doing different to what they're actually revising. Their clients actually buy houses and they buy homes they're living in. And three, the reason they've got all those toys and that success is because they're selling you buyer's agency services. It's not because their property portfolio is going through the roof.
And I think that's unfortunately what's happening is that the attraction of the ideal or the vision or the mirage of success is encouraging other people to come in and basically follow a lie because it's not what has got them the cars or the toys or the house is their properties.
It's actually their buyer's agency service.
it's a high ticket item to be charging $20,000 to $60,000 to do this. And if you're really transactional at $60,000, it's very easy to be a mega multi-millionaire really fast from the cash flow of your business. But it starts from also attracting people in the industry by...
by saying things like go from a barista to a buyer's agent and earn $750,000. It's all about how much money you can make.
It's never about how you've impacted someone's wealth creation in a positive manner and how you've supported that person to make a decision that they might have otherwise made a mistake on. It's just all about self greed, really.
And I struggle with that because that's what I saw a lot in the real estate agency game as well. It was all about the car, the watch, the suit. the European holidays, and it's just a wank fest. And that's a big part of the reason why I got out.
It's another big part of the reason why I moved from the eastern suburbs in Sydney and went to the Gold Coast, which is just a lot more down to earth and chilled and get away from the egos and those types of things and can concentrate on adding value to our customers and doing it the right way.
So I'm very comfortable with that, but I understand that's going to come at the cost of probably a much bigger business that I could otherwise build if I wanted to be focused on volume.
I don't think so. I mean, the challenge, I think, with building a buyer's agency is just making sure you've got a lot of great talent, right? And I think great talent do want to work with good people. So I do think it's, you know, you still build a great business.
You just don't have to do it the wrong way, I would say, is sort of my take on it. I mean, I think one of the challenges with this borderless sort of buyer's agency sort of
positioning, I would say as well as a lot of them are just going for this next hot spot, the next place that the data says it's so good to invest. I mean, what do you think some of the challenges of that?
And what's your personal philosophy that you're trying to say to clients when you're buying? Like, this is the type of property that you want to sort of buy and hold? Or are you sort of suggesting buy and then sell and go other markets? Like, what's the Scott sort of green shoes philosophy?
well it's it's horses for courses is the simple thing it's the only way to do it properly that avoids being cookie cutter and it takes our bias out of the equation so the first thing that i do when i talk to the customers is understand their risk profile and understand what their financial goals are and understand if anything what they own currently that we're going to be adding to or need to take into into the conversation to give them balanced advice once we've
built that framework, then we can give them the right advice on how to go about de-risking that next investment so they can add that to continue to build their wealth.
The risk of going into the hotspot markets for me is that what doesn't seem to get talked about in the transactional buyers agent world is that if you're buying in these high growth locations, typically they're in regional lower socioeconomic or lower OSAD markets and at a cheaper price point.
So sure, those markets have got a statistically higher chance that they'll double over the next decade. So if you're buying for growth and extracting equity in a really quick timeframe, that's definitely a strategy for the right customer. And probably 10% of our customers, for example, would choose to do that.
But what not being said is typically that it's really easy for me to get you to buy one, Chris, and then show you that the equity is there to buy a second.
So I've collected two fees, but it's whether or not I'm going to be around to advise you on when to exit those dog shit locations when they hit an affordability ceiling.
And that's the bit that I'm seeing, having been in the industry a long time, is that clients are saying, they've come back to me and said, well, I'm now in negative growth.
This thing worked really well at the start, but I'm in what doubled or went up 40% in the first two years and it's gone down 20% thereafter.
So it's those more volatile markets that concerns me or the advice that should be given three, four, five years down the line to exit those and repurpose that capital. So that's part of it, I think is a risk of it.
So we'll talk to customers about basically, and I'm being very general in nature here because the discussion will be much longer, but essentially, you know, which bucket do you fall into? Are you manufacturing equity?
Are you turbocharging and extracting equity process between one and four years, at which point you'll be selling that asset in, say, typically three to six years if it's done its job? Or are you buying in an early stage growth market?
And when I asked those questions all last year, leading up to the October launch of Green Shoots, 90% of my customers said, I'm bucket number three. I want to de-risk it. I want to buy at an early stage of the market and I want to hold onto those assets long-term.
I say, okay, great. Well then what's your natural bias? Are you naturally drawn to a capital city market? Are you open to regional major metros? And I'll talk to people openly like that to gauge where their comfort level is. Cause this is about you and your money, right?
I'm going to give you my professional advice. But I'm going to take you on that journey and give you all the opportunities and I'll give you the advice and talk about the negatives about each of those strategies as well.
So if the customer is saying then they want to buy in green shoots, then I'll talk to them about, you know, you're looking for properties that you can add value to or are you wanting to try for something that's set and forget and vanilla.
Again, almost everybody is vanilla, set and forget poor and they're busy with family, busy with life. And they want to be hands-off investors as best they can. They'll likely never see the property in their life.
They don't have a personal connection to it, so they don't need to be near it to maintain it. So then that drives us to look for what we buy en masse, which is less than 20 years old, low capital expenditure risk, single level brick homes and that are in very affordable markets.
And affordable, I mean low years to own, not affordables in low price. So the average customer asks is spending $760,000. And right now, this changes all the time, so don't hang me on this, but right now they're predominantly buying in West Melbourne.
So that might be Point Cook, Williams Landing, those types of markets that have got a very high ERSAD. So we can buy in nine and 10 ERSAD markets, which means you've got
white collar workers, but you're in a market in Williams Landing, for example, where the average years to own is just 29 years to pay off a mortgage.
So you compare that where I am in Miami, we've got a nine out of 10 ersat that it takes 90 years to pay off the average mortgage. So when you buy in those more affordable markets, then you can really paint the picture that you've got both cohorts competing for.
Price growth, capital value is increasing. So investors and owner occupiers, you've got a really low impact property that's going to have a light chance over the next five to 15 years of replacing roofs and kitchens and bathrooms. And that sits very well with people.
And the fact it's in a capital city market also gives a lot of our customers a great deal of confidence, even though I just said to you before, that's been debunked in terms of outperforming from capital growth.
Let's unpack this a little bit. So the, I think you're absolutely right. I think the buyers agents out there peddling, you know, particularly second, third tier, fourth tier regions. And what I say by that is just to the fundamentals of those markets, you know, scarcity, growing population, income growth, jobs growth.
risk, et cetera. And they've gone from the sister cities of the capital cities to complete regional towns to complete second tier regional towns. Right. And you're right, they look great on paper. Potentially they can manufacture it pretty good, particularly if they move those markets with a lot of buyers at once.
And they basically manufacture that growth without even touching the property. It's just them driving prices up. They will naturally get to an affordability challenge for that area. They've moved on. They've moved on to the next pocket and the locals just don't want to pay the current prices, right?
And so then they naturally have to correct to what locals will pay. And often they just won't pay the prices they've been pushed up to. And so they can correct. You're right, the buyer's agent's moved on. The buyer's agent within the buyer's agency has absolutely moved on.
But the issue they've signed up the client on is buy and hold. They haven't signed it up on, hey, buy in here and we're gonna sell it in three or four years. That's not what they've been told. They've been told this is a long-term growth play
And because the client doesn't want to buy and sell and buy again, they just want to buy and hold, which is what you said.
So I think they're mis-selling that type of service because it's basically a greater full theory momentum type investing that you're trying to basically, you're manufacturing the growth with other buyer's agents.
But you've got to get out before the party stops and you've got to, otherwise you're just going to go and buy a data asset that sits there. I mean, your strategy, I think you're absolutely right.
Like most people do just want to get something that's very low maintenance, something that's solid, that's something they can sit there and have no problems renting at all. and they're likely to get growth. How do you determine whether you... I mean, a lot of investors' budgets are limited.
So this has been a real challenge for us is that borrowing capacity has dropped dramatically over the last three, four years. Client's appetite, they still maybe wanna upgrade their homes. They don't wanna spend too much on investment or they're concerned about having a lot of debt with higher interest rates.
not only are they capacities down, but they don't want to spend. So that's also pushed a lot of buyers clients into lower price points. But is there an alternative strategy there where you go up to a higher price point or you don't think that's good because of the lower yields?
Or how do you sort of deal with that one?
Well, again, it's depending on the client's unique and bespoke needs, right? So we have to weigh up so many different metrics like that to make a value decision that we feel is the right fit to de-risk their strategy going forward. So there's a lot of moving parts.
We charge a flat fee for service. I think that's important because then we haven't got a horse in the race in terms of what you spend. So yeah, we can do this at 450,000 or we can do it at $4 million.
But the vast majority of people sit in that six to 900 range, because again, if you buy the right supply demand metrics and the right socioeconomic scores and the right stage of the growth cycle, they've got the best chance of sprinting to growth rather than typically the higher valued investments that would be over a million dollars in more mature markets and more established markets.
And I think most people are spending at that range as well because for the reasons that you just said, it's more affordable for the vast majority of Australians.
The problem with spending less than that for me is that for a lot of people to address the point that I said, they're not comfortable going to very regional areas. Some of the banks require a bigger deposit in some of the smaller locations as well. That can be prohibitive.
And then it's very cyclical for those markets. And we've just discussed why a lot of people aren't comfortable getting in and having to time the market to get out of it. So these are all points that we would discuss openly.
But the problem for a lot of the properties that you see in the regional areas is there, and again, very general in nature, this comment, but if you're buying in say 400 to 600,000,
It's a lot more timber homes, older style homes, risks of capital expenditure. And then when you start putting a new roof or a new kitchen into a $400,000 house, it's a very large percentage of the overall value of that home.
So that tends to put a lot of first home buyers or rent festers out of those markets. And they try to push to a higher price point so they can get into a better quality brick home.
Yeah, absolutely. I think when you start going lower, I mean, you get the lower quality, scarce, not as scarce land, that's why it's cheap.
And then two, the quality to build and the maintenance, and it could be absolutely wipe away any growth, particularly if that market and the cost to build and cost to, you know, the cost to do a roof, it's not that much cheaper when you go to these regional towns, the cities, you know, say Capital City ends up,
Yeah, I think absolutely that's something that burns a lot of lower price point.
I mean, going up, I do find in that middle section, sometimes there is some issues with scarcity. You know, there's, you know, maybe land release that can happen nearby. But I think what's happened is save those markets.
It's the cost to build and the cost to develop land has just gone up so much that... newer land is actually smaller block. So you can, you know, it's a 300, even Stockland came out in AFR last week, basically saying their new housing estates are going to be smaller blocks than ever.
And they're going to be townhouses.
Like this is the only way they can sell them. That makes sense as well. That's what we need in Australia. More of those more affordable, you know, middle price properties. But it's interesting as well, because 18 months ago or 16 months ago, I was buying a lot in Truganina.
And when I talked to other buyers agents in the industry, they'd shit can Truganina straight away. I'm like, okay, that's interesting. Well, over the last 10 years, Truganina has done double the Australian house price growth at that point, done 125% growth year on year.
It's never gone into negative territory, so it just keeps on trucking on or trucking on, I should say.
That market is a turnoff for a lot of people because it's a master plan community. It's predominantly Indian tenants or ownership, which for me makes absolutely no difference. There's a lot of sort of casual racism that comes into that from Australians and from an investing viewpoint.
But if you talk about supply risk, which is what you just referenced there, and also even vacancy rate, both of those are a second tier indicator to capital growth, right?
So people will put a red line through Tricanina because they had at that point a six or six and a half percent vacancy rate. And because it had nearly 9% supply risk, new supply risk.
And if you look at the suburb of Trugganina, one of the biggest suburbs in Australia, split down the middle by Leakes Road. South of Leakes Road, it's been built out for the last 20 to 25 years. So there's very little to none in terms of supply risk.
North of Leakes Road is cow paddocks. So there's a huge amount of supply there. But over the last decade, when they were building out the southern end of Trageena, the supplier risk must have been worse than it is today. And over that time, it's still double the Australian average.
So we look at these things, but go deeper into the data. And for me, that was an opportunity from an experienced agent's perspective. It's like, well, actually, I can look at the data, but the buyer's agents are following the same filters. So they're They're eliminating it on vacancy rate.
They're eliminating on building supply. But I'm looking at those things as an opportunity, if I can find the way to overcome those things.
So the way to overcome those two challenges in that suburb in particular, why I was buying there was because if we buy south of Lakes Road, we get rid of the supply risk. If we be incredibly conservative with our rental estimates, we'll lease these things on the first week.
And we were doing this consistently. And then that market was really growing. And now all of a sudden, there's just a rush into... Williams Landing, Point Cook and Trugganina in terms of 12 to 15 months later, they're now the top performing suburbs on a couple of the major data platforms.
So, you know, the professional buyers are catching on to these things as well.
Absolutely. I do think, soon as you see what happens to CGT, negative period, blah, blah, blah, but you know, ultimately there's still going to be a lot of people that are, you know, wanting to use property to build wealth.
And, you know, they are pushing down to lower price points and there's naturally an affordability cap that's happening across our capital cities to a certain extent. And that is really limiting supply, right? And developers are
You know, those farms you talk about, they've all been land banks, they've all, you know, and they don't release them until they can make a profit on them, right? So the market never often gets under, it's often undersupplied for housing estates.
Apartments have sometimes had issues with oversupply, but it sounds like you're not going anywhere near the apartment market, et cetera. Scott, it's been a good chat. I do appreciate you coming on. I do think there's a lot of value buyers agents out around negotiation.
You've done a business around that, but also this borderless buyers agency.
It's something I still haven't figured out, but it was good to unpack a lot more detail today. Thanks, Chris. Thanks for having me on.
Thanks so much for listening today. We hope you got lots of value out of it. If you'd like to speak to our guests today, there's links in the show notes on how you can get in contact.
And if you're buying your first home, upgrading, renovating, or need any finance-related queries, obviously we'd love to help. There's links in the show notes to us as a mortgage broker, and we look forward to next week's episode.
Key takeaways
- Aggett spent 23 years as a selling agent across more than 4,000 transactions before moving to the buying side, and will only hire buyer's agents who have held an agent's licence.
- He sets up a negotiation on three things: vendor motivation, buyer competition, and the sales agent's own motivation.
- He said his business buys about 10 to 15 per cent off market and rejects claims of 83 per cent, because a career agent charges a premium to sell behind closed doors.
- Buying under bank valuation was described as a vanity metric, since borrowing against a generous valuation means borrowing above the price you have just set.
- Volume driven agencies were described as buying 50 to 100 assets a month in markets that do not hold that many worth buying, with wait lists and pre approval pressure used to close deals.
- Ninety per cent of his clients last year chose the buy early and hold bucket, spending an average of $760,000 on low maintenance brick homes in markets that are affordable by years to own.
Who is Scott Aggett of Green Shoots Property?
Scott Aggett has been in real estate for more than 30 years, 23 of them as an agent in Sydney and London, across what he put at over 4,000 transactions. He sold out because he saw buyer's agents rising in Australia, and as much smoke and mirrors on the buying side as the selling side.
What followed was Hello House, a negotiation as a service business he ran for seven years, mostly owner occupiers, about a quarter investors. It was acquired by Listing Loop, then by Lendi and Aussie Home Loans. Green Shoots, launched last October, is the investor focused business that came next, built around buying six to 18 months ahead of the market.
He said he will only work with a buyer's agent who has held an agent's licence, because an agent negotiates against five, ten or twenty people in one campaign while a buyer's agent gets a single go.
I find it shocking, Chris, that you can be a licensed buyer's agent, or an award winning buyer's agent, and only have ever acted on one side of the process, and you have no idea what's happening to you in real time.
Scott Aggett, 6:42
What Should a Buyer Check Before Negotiating?
For Aggett a negotiation is less about comparable sales than psychology. He described three pillars: the vendor's motivation, the level of buyer competition, and the motivation of the sales agent, which he said nobody talks about. Is that agent transactional, or will they fight for the vendor?
His Gold Coast example was a client who found her property two weeks in. She emailed to say she felt bad about paying him, because the agent had said 1.35 would close it. Aggett said a two minute call established the three pillars, found no buyer competition, baited the agent lower, and saved $25,000.
The accountability sits on the analysis. He said the team prices manually to a $5,000 increment and tracks the variance against what clients pay. His other rule is to get to the client first: raise the red flags yourself and bring solutions.
| Measure | Quoted for the wider market | Quoted for his own business |
|---|---|---|
| Overpayment in the buying process | $50,000 per $1 million spent | Priced to $5,000 increments, variance tracked monthly |
| Time to close a purchase | 10.1 months | 3 to 6 weeks on average |
| Share of purchases made off market | 83% claimed in marketing | 10% to 15% |
| Buyer's agency fee | $20,000 to $60,000 | Flat fee for service, amount not stated |
As stated on air at 7:18, 13:40, 13:58, 20:32, 28:52 and 38:01. Figures as quoted by the speakers.
Does Buying Off Market Save You Money?
The statistic that frustrates him is the claim that most purchases are made off market. His business does around 10 to 15 per cent, he said, because there will always be a few motivated sellers. What he rejects is 83 per cent, or even 40 per cent.
The reasoning comes from the agent's chair. A career agent wants four weeks in the sun to meet the neighbours and generate the next listings. Selling behind closed doors gives that up, so the buyer pays for it.
So any career agent that's selling off market is going to make you pay a premium for that.
Scott Aggett, 21:37
He put buying under bank valuation in the same category. A generous lender valuation tool can make almost anything look bought under value, he said, but borrowing against it means borrowing above the price you have just set. The same goes for a message six months on showing a higher valuation, which ignores buying and selling costs, fees and capital gains tax.
Why Are High Volume Buyer's Agencies a Problem?
The bigger issue he described is volume. Agencies focused on numbers will buy 50 or 100 assets a month in a market that does not hold 50 or 100 worth buying. What he hears from their clients is cookie cutter advice and compromises on flood and bushfire zones, busy roads and roundabouts. He also described long wait lists, a 90 day pre approval allowed to wind down, and the threat of going back to the queue if a client says no.
On hotspots, his concern is what happens after the growth. Cheaper regional markets can double faster, and he said that suits roughly one in ten of his clients, but the client sold a long term hold is rarely told when to exit once a market hits an affordability ceiling. He has had clients return after a market rose 40 per cent in two years and then fell 20 per cent.
| Bucket | What it involves | Timeframe as described |
|---|---|---|
| Manufacturing equity | Adding value to the property to create equity | Not stated on air |
| Turbocharging and extracting equity | Extracting equity from a fast moving market | Equity extracted in 1 to 4 years, asset typically sold in 3 to 6 years |
| Early stage growth market | Buying early to de-risk and hold | Long term hold, chosen by 90% of clients asked |
As described at 32:44 to 33:19. Descriptions and figures as stated on air.
What Do Most Property Investors Actually Buy?
It's horses for courses. It's the only way to do it properly that avoids being cookie cutter, and it takes our bias out of the equation.
Scott Aggett, 30:55
Ninety per cent of the clients he asked last year wanted the third bucket: buy early, de-risk, hold. Almost all want set and forget, he said, because they are busy and will likely never see the property. That points the search at homes under 20 years old, single level brick, low on capital expenditure risk, in markets he calls affordable by years to own rather than by price. That age filter may matter more later: another episode asked whether energy ratings and disclosure rules will start to move the value of older stock, and what retrofitting costs. The average spend he quoted was $760,000.
His worked example was Truganina in Melbourne's west, dismissed by other buyer's agents for a vacancy rate around six per cent and new supply risk near nine per cent. His answer was to split the suburb at Leakes Road: the south built out, the north paddocks. Twelve to 15 months later, he said, Truganina, Point Cook and Williams Landing were showing as top performers on data platforms.
Buying an Investment Interstate?
This episode weighs a local specialist against a nationwide buyer's agent, and what each is likely to miss. If you are working out how an investment property loan fits your borrowing capacity and your plans, our team works on exactly that.
Investment Property Mortgage BrokerSources referenced: Street Secrets, episode 30, "Scott Aggett of Green Shoots Property | Nationwide Negotiation", released 2026-04-01. Host: Chris Bates (Alcove). Guest: Scott Aggett, founder of Green Shoots Property and previously Hello House. Figures are quoted as stated on air and have not been re-checked against current data.
Press play on these