Curious about upgrading?
Wondering where to start?
Complex questions that need answers?
Is there a better structure for you?
"They managed to navigate my complex expat income and even got my Google RSU income approved as well."
"I highly recommend Alcove to anyone looking for a mortgage broker who is responsive, trustworthy, and truly cares about their clients. Thanks again to the whole team for making the process such a positive experience!"
"As founders, we're constantly jumping between things so having a partner that handled the details & made the process super clear made the buying process breezy for us. Very happy with the experience!"
“It almost felt like it was his responsibility to make it clear to me, not my responsibility to understand it.”
“I've been pretty much fully leveraged the whole time. So the sounding board on that, in terms of what was achievable, what wasn't — I think trust is just built along that.”
"Alcove has been a great partner. They look after my audience properly, keep things simple, and deliver real value. I’ve got full confidence referring clients knowing they’ll get honest, straightforward advice."
"Property is one of the biggest financial decisions people make. Alcove stood out because they take a strategic approach to lending - helping clients structure property and debt decisions in a way that genuinely supports their broader financial plans."
Adapted from audio. This article is a written adaptation of the original podcast episode. Sources and dates are shown with each figure.
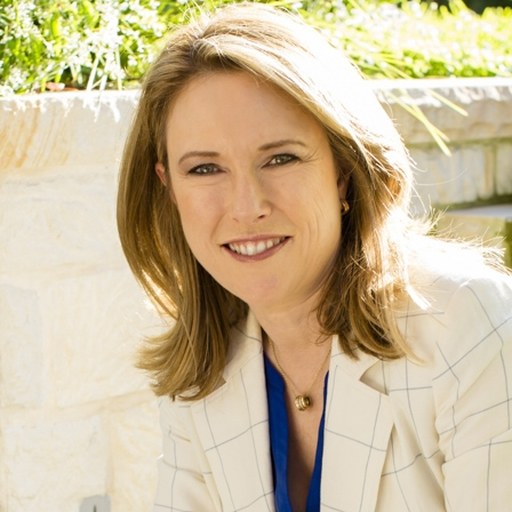
Co-host of The Elephant in the Room. Real estate agent, buyer's agent and buyer's agent mentor, co-host of Foxtel's Location, Location, Location Australia, author of Auction Ready and co-host of Your First Home Buyer Guide.

May Azizi on Whether Housing Can Be Fixed Without Hurting Investors
Anglicare Australia's May Azizi joins the show on budget night to argue that tax concessions, not supply alone, sit behind rental stress. Chris and Veronica test that against what happens to renters if investors step back.
He earns $80,000 a year, which sounds like it should be enough to live on. But after rent on a two bedroom in a middle ring suburb, he's spending 45% of his take home before he's brought home a single grocery. Too much income to qualify for help and too little to escape.
He's not an edge case. He's the face of a crisis that has quietly migrated from the margins to the middle. And the question is why a country spending billions subsidising property ownership keeps failing the people who simply need somewhere stable to live.
Today's guest, May Azizi, gets her intelligence from both sides of the problem. As Deputy Director of Anglicare Australia, she sees the 24,000 people in her network that are caught each year before they fall through the cracks.
And as national spokesperson for Everybody's Home, she's inside the policy debates where fixes get argued over and watered down. What makes this conversation worth having today is that housing is one of those problems where every credible solution seems to drag a new problem behind it.
And since governments have spent four decades retreating from housing with investors stepping in to fill the gap, is it time for those very investors to pay the ferryman? Welcome to the elephant in the room.
This is the podcast where we love to talk about the big things in property that never usually get talked about. I'm Veronica Morgan, real estate agent, buyer's agent and buyer's agent mentor, co-host of Foxtel's Location Location Location Australia, author of Auction Ready and co-host of Your First Home Buyer Guide.
Hi, I'm Chris Bates, ex-financial planner and mortgage broker, currently ranked number three in the annual MPA Top 100 Mortgage Broker Awards. Before we get started, everything we talk about today is not personal advice, and we recommend you engage the services of a licensed and experienced professional.
May is easy. We've had many conversations on this podcast about solutions to the housing crisis. As spokesperson for Everybody's Home and Deputy Director at Anglicare Australia, you will no doubt add another perspective to this discussion. Welcome to the elephant in the room. We're excited to have this conversation with you today.
Thank you so much. And can I say your intro was spot on. I loved everything you said. I don't necessarily agree with it, by the way, but we'll get into that.
Mate, thank you so much for coming on. Just for, I guess, a bit of context, this is budget night tonight. We're closing at three o'clock. This is not when your listeners are hearing that.
So, but we can sort of assume things are going to happen tonight based on all the sort of the media sort of storm that has been created. But I mean, but putting that just to one side for a minute, I mean,
In your view, the Australian property market and the failures of it, I mean, what do you sort of see on the ground, really feel where we've got it so wrong and where the conversation isn't talked about enough? Yeah.
Well, I suppose one of the things, well, the big issue and I guess the thing we hear from a lot of people, we as in Everybody's Home, the campaign, what we hear from our supporters, people who email us, we get emails every single day.
We are becoming a country where only the very wealthy can avoid rental stress. And you can see that with each passing year, with each passing decade, that problem becomes more and more pronounced.
You know, we used to be a country where a person on an average income could very comfortably afford to rent a home and buy a home. And today we're a country where some people own more than one home, where taxpayers really underwrite that investment for some people.
And there are other people who are earning, Veronica, exactly as you said in your introduction. pretty decent incomes, but are actually in what we would consider to be rental stress.
We did a piece of research at Everybody's Home last year that found that if you're living in a major city, you would need to be earning over $130,000 a year to avoid rental stress. That's as a single person, obviously. Couples can work some things out and make some savings.
And if you're in a regional area, it needs to be $110,000 a year. So we've got some pretty serious questions to ask ourselves when even people who are on pretty decent incomes can't avoid rental stress.
So rental stress is caused because the rent that you have to pay forms too big a portion of your income, right? Unless you're on a very high income. So I should put that caveat on it.
If you're on a very high income, probably doesn't, you know, spending 50% of your income probably doesn't matter. Oh, I see. Yeah, okay, that's fair. You have much more discretion.
If you're on an average or a low income, and that's an important part of the definition, yes, you do need to have it be 30% or less. Yeah, that's a good distinction. Thank you.
The thing is, though, and this is something that I often find interesting in debates I hear around property, is that interest rates go up, for example, and some people start saying, oh, well, landlords are going to start putting up rents. Well, it doesn't work that way.
The landlords can only put up rents if the market can bear those rents. And I guess you can still argue that with that many people in rental stress and obviously the market isn't bearing it, but they are still paying it. So in some way or another, it's been born, right?
But what we are seeing is with increased pressure on investors and financial pressure on investors and with interest rates going up and all the rest of it, that there are, and certainly if you look at Victoria, for example, there's been a bit of a sell down in investor stock. Yeah.
then that's going to also put pressure, output pressure on rents as well, right? So what I saw, I think I saw you roll your eyes there. Had a think.
Well, the thing though is that, and you know, in the introduction, I said that in four successive decades, governments have retreated from public housing and social housing, right? And so the burden has been placed on individuals to provide rental stock. If you have less rental stock, rents are going to go up.
So what is the solution there? So there's quite a bit in your question.
I guess the thing that I would take friendly issue with is rents in Victoria are actually stabilising, certainly not depending on which measure you look at, either stabilising or certainly growing less slowly than they are in other parts of the country. So I don't think it's had that negative impact on rents.
The ACT has brought in some minimum rental standards, limits on rent increases, and we've seen that that's had a a good impact on the ACT.
Nowhere in the country is very affordable, but these are parts of the country where rents are either not growing as fast as they are in other parts of the country or starting to stabilize, which is a good thing.
So I don't think it necessarily follows because when investors move out of the market, that house doesn't dematerialize. A renter who might have been saving to buy also leaves the rental market. That house is available for somebody who wants to live in it.
whether it's a first-home buyer or some other kind of owner-occupier. So it's not having that disastrous impact on rents that a lot of people have predicted. There's a couple of factors there that I wonder if you've sort of factored into the analysis of that. And one is the household composition.
So households, renter households typically have more people in them than owner-occupier households. So you might lose a rental property, which might house more people than the owner-occupier that then moves in. So then that does displace more people.
But the other thing too is that Victoria has sort of led the way with their tenant reform, legislation reform, and New South Wales has got some coming through. Obviously, ACT has as well. Queensland has too, and potentially other states.
So when you do start to put restrictions in terms of how many times you can raise a rent in a year – so i.e. limit it to once a year, once in a 12-month period, then that is obviously going to slow down rental growth, isn't it?
But that's an intervention that will have an impact when it sort of takes form, but then over time that will get smoothed out. Would that be fair to say? Yeah, that's part of it.
I think the other part of the picture, I mean, you touched on some of the tax issues in your introduction.
One of the things that has accompanied the tax changes that have come in over the past couple of decades, and I'll be really interested to see whether there are some changes to wind them back in tonight's budget, as everybody says, a different kind of landlord has been investing for the past couple of decades.
So in the 80s and 90s, most landlords in Australia were positively geared, which is as your listeners would well know, they owned their investment property outright. They were making money from rents.
And back in that era, rents were not growing anywhere near as fast as they have been for the past couple of decades and especially past 10 years. For the past 10 years especially, we've been seeing annual rent increases for asking rents in the order of about 10% a year.
And it's hard to attribute exactly why that is, but I believe and our campaign believes that a big part of that is that we've got a lot more very highly leveraged loss making landlords in the market now than we used to.
And they're much more sensitive to things like the interest rate increases that you mentioned before. They will charge whatever the market will bear. They tend to be slightly less responsive to their tenants than other landlords. So that's also a big part of the picture.
Who's investing and, you know, to what extent can they withstand the financial pressures? How sensitive are they to their own cost increases? That's also a big part of the picture as well.
Let's just assume the budget tonight goes through and they may change the capital gains tax, which is almost, you know, makes property less attractive and maybe they do it to other asset classes. But let's just put that to the side. And they make changes to negative gearing.
Like at the moment, apparently it's going to be no negative gearing, but negative for new homes. I mean, how do you feel about that policy and does it make you guys really happy? Where do you think it's going to make the biggest difference around the country?
Like in terms of, and what is it actually going to do? And then what is potentially just some of the unintended consequences, which is just... I guess the challenge of when you're making changes like this, it is going to impact certain things.
You know, it doesn't matter really what we think they should or shouldn't do. Like they're going to do what they're going to do. But if streaming, that's what they do. How do you see it playing out, I guess? And where do you think it's going to really help us as a country?
So these are changes that we've been calling for for a long time.
We've been calling for the government to wind back the capital gains tax discount, and it looks like what they're going to do in the budget, you know, knock on wood, is going to be pretty positive on the capital gains tax discount.
The negative gearing changes, it looks like they'll be a bit more heavily grandfathered and that people who are current investors will have a few more protections as opposed to people who might be coming in after... after budget night. So let's see.
Grandfathering is an interesting one because you could argue that it actually makes the inequity worse by protecting people who've been able to invest to date and then kind of closing the drawbridge up on everybody else.
But I mean, on the whole, I think these will be good changes, good for equity and hopefully can raise some money for the budget to then invest in rentals that people can afford.
I think the big change is that for people who are wanting to buy, they will no longer be out there competing with investors who are enjoying the benefits of a lot of public tax subsidies.
And again, as I'm sure you're both very well aware and many of your listeners are well aware, negative gearing especially is part of the tax strategy that landlords use to make their investments viable. So if some of those more highly leveraged investors move out, I think that
It could be a really good thing, actually, for arresting some of those rent increases and especially stopping this kind of prodigious growth of house prices, whether they come down or whether they just stop growing at this insane rate that they've been growing at every year for the past couple of decades.
That would be a good thing for the country. The thing that you need to do on the other side of that, though, is have the government really step up and invest in rentals that people can actually afford. So that's the other side of it. Our campaign is about both of those things.
If you look back at the history of housing affordability in Australia, back when we had affordable homes to rent and to buy, we didn't have... this capital gains tax discount and negatively gearing was not as widely used by investors.
But the other thing that you had was the government playing a really big role in housing supply itself. About one in three renters used to rent from the government right up until the early 80s. They used to rent homes to people at very high rates. They even used to sell homes to people.
Teachers, public servants, construction workers, all sorts of people used to be able to rent from the government and that was a big part of why housing was affordable. So they moved away from that in the 80s and 90s.
In the late 90s, these tax changes came in, and those are kind of two big peaks where you see housing affordability start to deteriorate. So addressing the tax side is one part of it, but you also need to fill that gap with the government stepping in and investing in housing themselves.
I would have thought. Is that one of your worries though? Like the government is really hard and expensive to build, right? And make it, and, you know, resources, whether it's Olympics or roads or, you know, high-end developments, et cetera. Like there's, you know, I guess there's a structural long-term thing that I agree.
Yep. We got to. And I absolutely agree that investors are competing where a lot of first-time buyers are buying.
So first-time buyers are going to open homes, they're getting access to the 5% deposit scheme, and they rock up and they lose it to an investor who can just basically not have to worry about the bigger mortgage, et cetera. And a lot of investors are targeting those areas. So I do think that...
First-time buyers in the market right now are going to have less competition, right, which is a good thing for them.
But if you don't replace that with more rentals, are you worried that the government's just like lag of affordable sort of housing that it then hits the most vulnerable or it hits certain parts of our rental community hard? And that's my biggest worry is that, you know, yeah, okay.
We've got some first-time buyers that are buying. Great. So they're good. They've got security, but there's people who can't afford to buy. You haven't got the money. You haven't got access to five, like you need to rent.
And, you know, yes, you know, you're encouraging more people to buy, but you're really potentially, they're going to maybe pay the price as well, which I, when they, you know, already paying a big enough price. I don't think it's going to have this big impact on rents that people imagine it will.
People will leave the rental market, remember. I mean, I think that's a big thing to remember. But I mean, if you look at the past couple of decades, I agree with you.
It's not, you know, I don't think that exclusively focusing on supply and demand, like a lot of people do, always makes sense for housing. Homes are not bananas. It's not the same thing. So I don't want to get... I don't want to get too hung up on that.
But I think if you look at the past couple of decades, these tax settings do seem to have really driven big rent increases. And it's hard to point to something else that could have happened at the same time to have driven them.
So I do think that winding them back will be important for rents. It is critical that the government does invest in public and community housing, affordable rental options to fill that gap. If they don't, I don't think that what's going to happen is that rents are going to get more expensive.
I guess my fear is that there will be a big group of people who hear the government trumpet these changes, you know, we're fixing housing affordability, and then in five or ten years you look back on it and say, not a lot's really changed for me.
And I think you can lose a lot of confidence that there actually is a solution out there to this problem. I don't know if it's something that you guys talk about on your podcast very much, but I think that's...
that loss of confidence, that loss of trust is driving a big, you know, a lot of this discourse around immigration. You know, I think that's when people get frustrated and they start looking around for what other causes might be responsible.
So I do think the government, if it's going to trumpet a budget like this and say, you know, we're really making housing the centrepiece, we're focusing on it, we're tackling housing affordability, it's important that the things that they do actually achieve that goal. And so tax is one part of it.
They also need to start building housing.
100%. And that's the reason that we've needed so many investors. But it's not just the capital gains tax and negative gearing changes. It's not just international migration. It's not just any one of those things. It's also about access to credit.
Now, that has changed markedly over the last 25 years as well. So in terms of the actual prices of properties, that's a huge, huge factor, but it's not actually talked about at all in these debates. So I don't hear it very often mentioned at all.
And I also, I wonder about this idea about, well, rents, because... If you're negatively geared, that actually is giving the landlord a relief on their cash flow.
So the incentive to put up rents in order to cover costs, those two arguments don't sit side by side in my view. And also I've remembered because I am a landlord and I've been in the property market now in the industry for 26 years, I'm looking back to COVID.
Like I'm in Sydney, in the years before COVID, there was a huge development of apartments and that did have downward, that created huge downward pressure on rents for pretty much anything that was one or two bedroom houses and apartments across Sydney, not just in the suburbs where these new buildings were built.
And we really, really saw that with this influx of stock, right? And so we all had to drop our rents. So it's not actually, you know, you might look at a chart, aggregated data across the country might say rents have been rising ever since when, you know, 1999.
But there's been plenty of peaks and troughs in lots of different markets that behave different ways. Landlords can only charge what the market will bear. And I know that from experience, personal experience, but also industry experience at the coalface.
So I'd like to separate that sort of housing affordability from a purchasing point of view, as in the property's value and the actual rent that somebody is able to charge the market. But I'm also interested too, because what you said makes me think,
that you know really ongoing if there is less rental stock around you're not necessarily agreeing that there is but i think that compositionally there's been a change i think a lot of people that have been selling out like if you look in melbourne for example a lot of people are selling are actually selling sort of more established houses and bigger bigger houses and a lot of the investors coming in are buying the cheapest stuff and they are competing with first home buyers so that means the available properties for rent that the whole composition is changing but
People then who could afford a bigger house, if there are less big houses around, for argument's sake, they're still going to need to rent. And they will then push people out of the lower tier of properties, if you like, if there's nothing available, you know, for their budget.
And that's going to have a knock-on effect down the line. Is that what you're seeing at the coalfaces, you know?
Again, that does put pressure on people with what would seem to be a good income, but that sort of then makes properties unaffordable because you've got people that have got more money than they do, bigger incomes than they do, being able to take the stock that they would normally go and live in.
Is that something that you're seeing? It's a bit hard to gauge these kinds of differences for the sorts of people who we look at. You mentioned earlier that in my day job, I work at Anglicare Australia.
We put out a rental affordability snapshot every year and we put out the latest edition of it last Thursday. And
we look at 14 different household types on low incomes. We also do an edition focused on key workers, so people like teachers, firefighters, et cetera.
But the one that just came out looks at people on minimum wage, couples, if you work full-time, get the minimum wage, get the family tax benefit, people on Centrelink payments. And if you're a single person on the minimum wage, there's been really nothing but a deterioration
like a steady deterioration in every part of the country. Like we break it down for every part of the country. We look at all of the rental listings that are listed on realestate.com.au in a sample weekend.
And it's kind of hard...
To see, particularly for people on Centrelink payments, it's just been 0%, like 0% every single year. We can't really see a change. For people on the minimum wage, I think that's a fairly good gauge.
You know, we were looking at a situation where they could maybe afford one in every five rentals about 15 years ago when the snapshot started, and now they can afford less than 1%. And that's a fairly consistent picture right around the country. It's been a steady deterioration.
Perhaps from a landlord's perspective, you know, you might have had to have not done a rent increase because a particular factor is in your local area one year or reduce it a bit. But, you know, on the whole, we're not seeing people's experience of affordability decline year on year.
But if there was more properties available... That wouldn't happen. That's not the case. No, no. Last year, we actually had a 10% increase in the number of listings that were available and affordability was down.
And again, during the COVID era, we had double the number of listings, like an enormous number of vacancies, and they were not going down. So this is what we were talking about before. It's not just a simple matter of supply and demand.
As you say, it's about what the market will bear and people will do what they need to do to pay the rent. and keep a reef over their head.
So May, I've got a bit of a conspiracy theory and I'm not sure whether you were engaged with the government in terms of their consultation around like negative gearing and CGT.
Like from what I could see is, you know, there was an inquiry and a lot of people put submissions in, but they didn't do too much of the industry sort of, you know, what do you guys think about all this?
So I'm interested to see whether you were consulted as part of Anglicare or Better Homes. I feel like their frustration has come from the displacement in regional communities, particularly because over the last four or five years, investor lending has gone off the charts, particularly at low price points through the proliferation of
you know, marketing, prize agency, sort of investment, build wealth.
A lot of them are younger people using rent vesting as a strategy, but they're obviously targeting lower price points, which forces them out of the capital cities and buying in regions and, you know, and pushing prices at what fast, what locals can afford to buy in.
And, you know, so it's kind of capital cities buying out the regions, you know, future homes. Have you sort of got any thoughts on that? Because You know, a lot of these investors haven't been sort of spending more than sort of $700,000, $800,000, $900,000.
They have been sort of going to the fringes of the capital cities or the regions. Is the question about renting, like the impact it's having on renting, or is it about crowding out buyers? Well, both.
Well, I think that I feel like this is kind of what's driving because, you know, one of the things about housing affordability is, right, you need to give people options, right? And so... capital cities are getting too expensive. We need an alternative option to, whether it's houses or apartments.
And one of the options people would consider is, okay, for my income and what I do for work, I need to move somewhere a bit more affordable. I'll move to like a sister city to a capital city.
So I might move to Ballarat or I might move to Central Coast or Newcastle, or I might go completely regional to Bendigo or Mildura or Townsville or And those are basically where a lot of the investors have been going for the last sort of four or five years.
And if you were in those communities, if you owned a property, you'd be like, yeah, great. My place was worth $500,000. Now it's worth a million bucks. I can't really ever buy anything else. But I can't move anywhere else because I'm already in a region.
But if the kids are them or the people renting in those communities, they just know that it's gone past what locals can afford. So I was just wondering, has that been wrapped up Obviously, there's a capital city rental problem, but I feel like it's moved to a regional investment problem.
I just wonder if the government are just really a bit upset by that because it's really kind of displacing our regions. They've already displaced our capital city, but now we're taking away the second option. Yeah, 100%. I do agree with you. I mean, I think that manifests in a lot of different ways.
I mean, I think you see one of the trends we saw during COVID was people who had been living in the city and who work in the city and who earn city incomes once working from home became more kind of widely accepted and something that it was more possible to do.
And people started moving further and further out. And as you say, exactly kind of displacing and competing with locals, whether that's to rent or to buy. But, you know, certainly we saw the impacts of it in the rental affordability snapshot and also in that priced out report that we do for everybody's home.
and you can see that it's not necessarily more affordable to rent or buy in a lot of those areas, especially if it's like a commuter sort of town that's where you can easily get to Sydney or Melbourne.
I personally have friends who, you know, live in Melbourne and decided a couple of years ago that they can't afford to buy anything in Melbourne but were concerned about their retirement. So they bought a place in...
Oh, I can't remember, but it's a town that's about maybe 90 minutes, two hours away. And they thought, well, we'll live there when we retire. This will be kind of an investment, like a retirement investment sort of strategy for us. And that's fine for them.
But for people who live in these areas, you could only imagine it's creating a whole lot of issues.
And I think Tasmania has been experiencing that for a long time. Tasmania has certainly caught up to mainland in terms of prices, but there was a period 10 or 15 years ago where a lot of people on the mainland were investing in Tasmania.
And huge issues for people who live there because, as we know, incomes in these areas are just not as high as they are in the cities. So it's hard for them to compete with people who don't live there. I mean, in coastal areas too, the Airbnb and the short-term rental as well.
So you've got quite a lot of pressures on regional areas that are within a sort of a reasonable distance of a major city. And we've been talking about that in the podcast for many years as well.
But also there's been this proliferation of buyers agents that have been buying in bulk in a lot of regional towns. And so that's You know, you could argue, oh, well, that should have a downward pressure on rents, you know, hopefully from the renters in the areas. And that might be a good thing.
But I guess for the owner occupiers who want to buy into those markets and the locals are being priced out because there's a lot of Sydney or Brisbane or Perth or wherever the money is coming from tipping into these markets. Is that something that you've noticed in your reports as well?
You know, the impact of buyer's agents is not something that we've explored before. I'd be really interested in looking at that.
And I'm always perpetually amazed at all of these like micro sub-genres of industries and professions that pop up around the housing crisis of different people who see opportunities to make money. I don't say that to everyone. Well, I mean, some of them are bad actors, but not all of them are bad actors.
Some of them are just people trying to make money. But yeah, I'm always amazed at the sheer number of people who find ways to get...
you highlighted before that the 20, 20, 30 years, the investor was buying a lot with a lot of equity, a lot of positive gearing, you know, you know, like access to credit was a lot different. So like that changed.
And then you had the, the 2010 boom, which was all the investors basically got bought off the plan apartments. Right. Which, um, you know, that they, They could have been building for first-time buyers, absolutely.
But they were building them so cheap and so poorly that basically they were putting them up as fast as they could. And that created a lot of rental accommodation, right? Because they're all sold to investors. And I think personally, that's why a lot of Melbourne rents didn't go up. They didn't build great.
properties that a lot of people want to own, but it created a lot of rental commission. You can see why the rents didn't go up. And the same in Brisbane. They flooded the market with apartments. It gave renters a lot of choice. And so they weren't forced to buy.
So if you haven't got this fluid rental system, you feel like, well, if I can't rent, my rent's going up. I've got vacancy rates. If I'm not the best rental application, I've got to buy. So your anxiety increases. But the investor for the last five years
Because they switched on to, oh, actually, these off-the-plan apartments aren't performing. I've got building issues. They haven't gone up in value. They've all shifted to all the regional locations, because it's all borderless. And I feel like it's having huge impacts on regional communities because... They weren't expecting this.
All of a sudden they've got all these East Coast money or money from other states coming into their community and completely changing the buyer and prices. And then the investor sort of says, oh, what's gone up there now? I'm not going to buy in Hobart anymore.
And they move to the next location and then they've created all these rentals, but it's pushed the prices up. And so... I think that it's just such a big change that I think has happened over the last five years that I feel like that's also driving what they're doing.
It's like they're almost like the regions who don't get part of the national conversation as much because they're just not in the capital city newspapers. But I feel like there's some huge problems that have been created that maybe they've been able to get those stories to the government.
Well, to go back to your first question, we did put in submissions, Anglicare Australia and Everybody's Home, to the inquiry on the capital gains tax discount. And more recently, there's been another inquiry on intergenerational inequality and the role of housing in that. So we put submissions in that calling for the tax reform.
Sorry, I forgot to... I forgot to say that. I got too excited about a couple of other things that we were talking about. But I think it is true. I mean, those regional impacts are enormous for local people.
I live in Canberra and, you know, I think for a lot of us who live in cities who stress out about whether or not we can afford the area where we are, you know, it is tempting to just look at a place on a map and go, oh, you know, I might just, you know, maybe I'll...
maybe this can be my plan. Maybe, you know, maybe I could do this. All of that has a downstream impact on people who live in these areas. And I mean, one of the things that we hear a lot from people who've done pretty well out of property, you know, people who are a
maybe don't even have a mortgage anymore, is they're really worried about their children and children can't afford to live anywhere near them. And we hear that from people who live in affluent areas like the eastern suburbs of Sydney.
You know, they've got kids who just can't afford to live anywhere near their families and their communities. But we hear it a lot about people in regional areas. And it's having a lot of downstream impacts that, I mean, I hope people are raising with government.
We did a piece of work at Everybody's Home a couple of years ago on essential workers and regional rents and found that, you know, rents are unaffordable for most essential workers. These are people working full time. Some of them are on pretty good incomes.
Teachers and firefighters are the highest income earners in that cohort. We also have some lower income earners, like people in retail. and hospitality.
And, you know, you can't really have a town or a community if you don't have people who can work in aged care or people who can work in your hospital or people who can, you know, work in even a cafe.
I mean, we found out during the pandemic a lot of these jobs are a lot more essential than we thought they were. So it's having a lot of downstream impacts in these regional areas.
So supplies is what politicians love talking about. You need supply, right? It's obviously not as simple as that.
But as we're talking, as you're talking about the amount or the proportion of people on lower incomes that can afford to rent has gone from, what, 15 years ago, 20% down to 1% in some areas and some other areas, zero. So that's rapid.
It's not like properties that they can't afford sit vacant waiting for a better tenant. And I use inverted commas around the word better. So it is a supply issue, clearly, because if there was enough available, then rents would be... less expensive, right?
But that hasn't been borne out by reality. I mean, I mentioned... Hang on, hang on, hang on. But you did talk about the number of listings that came on, but did you talk about the proportion of the demand?
The number of listings only matters if you can put it into context of how many people are actively looking. So the vacancy rate goes down. That sort of says to me that there's... there's more people out looking than there are properties available.
I mean, the vacancy rate is also, and listings is not, that's what's available to rent. That's not what is available in the total rental pool. They're two very different numbers. So I'm wondering if there's been analysis of that. The total stock number is one thing. The amount of listings is completely different.
I would say that there's the two aspects to that. I don't think that there's been a demonstrated relationship between either of those things. There isn't a relationship between the total amount of rental stock and the number of listings that go on the market.
We see that from the rental snapshot, but you can look at it any given weekend at the number of rental listings there are.
We have done quite a bit of building over the past decade, not necessarily over the past year or two, but the decade preceding that, Australia built a million homes, which outstrips population growth, including immigration, by quite a bit. At every census, actually, that we've
done on record since the early 90s, the number of homes per person has increased. We've actually never had more homes per person in Australia than we've ever had before. And that doesn't necessarily have a relationship to the number of listings.
And then again, when you look at the number of listings, that doesn't necessarily correlate to affordability. So I go back to the point that I made before. I don't want to sound glib. Homes are not like bananas. It's not just as simple as supply and demand. That's very true.
And that's why we like to have these conversations because it is often, you know, as I said, it's politically expedient just to talk about that. But the simple fact is there's a lot more going on there.
If we've got more homes than we have, the more than enough homes to accommodate the population that we have, where are all the surplus homes? Yeah. There's a couple of different answers. We have more homes than we've ever had. They're more unfairly distributed than we've ever had.
Wealthier people are taking up a lot more space than they ever used to, which is interesting because households on low and middle incomes are staying about the same size and sometimes getting bigger. But you find that wealthier people are just taking up a lot more space in homes than they ever used to.
There are probably, you know, more second homes, more holiday homes than there had been in the past. I don't want to overstate that. I do think the empty home issue can be a bit overstated at times.
I see it as a symptom of a problem rather than a driver of a problem in and of itself, you know, I think. And same with Airbnb. I mean, I think Airbnb, certainly in some regional areas, is a big driver.
If you're living in Byron Bay or you're living in Tasmania or you're living in particular areas, Airbnb is a driver. But for the most part across the country, I would say it's a symptom. It's a symptom of housing that's more unfairly distributed than it's ever been.
So, I mean, you've got the vacancy sort of homes that are basically a piece of land.
It's an old house that investors are sitting on because there's like, you know, and they're not even renting it as part of the rental or they're just letting it run down and they're cash renting it to some family member. Like there's definitely that, I think, needs to get fixed, right?
Because, you know, every land needs to probably...
You know, I guess the investors sitting there, they've got a piece of land, you know, they bought it, they bought it at a point, but I mean, I guess when we're trying, we've got a shortage of land, I guess, encouraging them to sort of, if they're not going to build on it, just sort of, you know, get someone else to build on it.
So I think that's a good move, but also there's all these spare bedrooms, right? And granny flats, like our whole tax system doesn't encourage you to rent a room out. Like, I just think that's crazy.
I think there's, you know, why, if you've got a little downstairs, you know, studio apartment that you could, you know, get two, 300 bucks a week and help you pay for your mortgage and help out a, you know, a friend's, you know, uni student that, you know, and get a couple, you can't even do that without affecting your capital gains tax exemption.
You've got to pay tax on it. So there's all these things. I guess, missed opportunities that they could easily make and create rental supplies straight away, but they just don't seem to get any air. I feel like they just get shut down.
I just don't know why sometimes they don't even look at the spare bedroom. I don't disagree with anything you've said, but I do want to circle back to something Veronica said a few times, which is that we rely on the private market and private landlords to do a lot more than we should.
It's really not their job to provide affordable housing, in my opinion. I mean, it's the government's job to do that.
We'll agree with you on that. You won't get any argument on that. Yeah. Investors are not investing to provide affordable housing. You know, that's not why they go into it. It's more of a charitable endeavour. Some people do.
You know, there are people who rent out to community housing providers and the like, but the vast majority of landlords are... You know, they're doing it to bolster their retirement or make extra money. Again, to circle back, Veronica, to something that you said earlier, you said there's no one solution.
If I would to gently push back on that, if you look back, if you look around the world at the countries that have either avoided a housing crisis, which there are actually very many of those, but there are some, or countries that are starting to turn their housing crisis around, they all have one thing in common, which is that their governments are major suppliers of housing.
They are not just leaving it to the private sector.
I think it's really good to look at all these things around spare rooms and granny flats and tax treatments and all of that. But I think at the end of the day, homes will not become affordable until governments take steps to make them affordable.
You know, the private sector, I think, doesn't have a track record in Australia or anywhere else of really doing that on its own without some intervention. 100% agree with you on that.
But how big is the shortfall though? The shortfall is like 600,000 homes we need. And what can they do? Best case, 20,000 homes, even 20,000 would be a lot to be building. I mean, they've had this sort of housing Australia, future fund. I mean, what have they, they basically built nothing with that.
So-
I think it's wishful thinking that the government's all of a sudden just going to come in and build 100,000 or 200,000 affordable housing and how they're going to fund it.
I just don't know how they're going to fund it and how they're going to compete for resources when we've already got roads and private and commercial and airports like this. There's already enough they're doing as well, but that's going to have to factor into their prices. Can the budget afford to do this?
I mean, a little bit, but when you've got 11.5 million dwellings, it's hard to move the needle when you haven't done it for so long, right? But I know you've got to get started somewhere. You do.
I mean, the government used to do this back when it had much less money, much less capacity. We used to build, the federal government in Australia used to build one in four new builds in Australia, about 30,000 homes a year. At the high point of construction, it was about one in four.
The whole system was actually built from the ground up very quickly after the Second World War. and run down relatively quickly. Everything we've ever needed to do to make housing affordable in Australia has actually been done in Australia. We don't even need to look overseas. It's all been done here.
The difference is that we're just a richer country than we've ever been. The federal government has this housing accord where it's got a target of 1.2 million homes in the private market for private developers to build.
If you can build homes in the private market, if we've got the capacity to do that, the government has the capacity to build those homes as far as in terms of the workforce. If that capacity exists to build in the private sector, the government can build in the public sector too.
It does feed back into another often touted cause for affordability, and that is zoning and freeing up red tape and film application processes. And so, again, that hasn't necessarily miraculously resulted in
in a plethora of new dwellings being built. And everyone's scratching their head going, oh, why is that the case? We've rezoned it. We've upzoned it. We've given them so many more extra floors, blah, blah, blah. And it goes back to the same issue in many ways is that there's a resource problem here.
But also when you're in the private sector, I mean, I've got one opportunity to get the most amount of, extract the most amount of return for that land that I've invested in.
I'm not going to go and develop it when the government wants me to develop, but I'm going to develop it when it suits me to develop it. So again, you're relying on... the private market to deliver when their motive is profit, right?
But also there's an opportunity there to do counter cyclical development for governments. You know, when it's too expensive to build, which it seems to be at the moment that for very many developers are saying it's unviable to build affordable housing. right?
So when we look in Sydney in terms of the rezoning here, and some of the developments that are getting approved and out of the ground are in the most affluent areas, and these are absolutely not doing anything to help affordability.
And you think, well, that's when the government needs to be stepping in and saying, right, well, we've got other ways to make it work. We don't need to make a profit. We also could save money, all the taxes that we're charging everybody. So
you know, the governments can get involved in a much more constructive way, I believe, but they've obviously been choosing not to. But I think our world is very different now to what it was when the soldiers came back from war and we needed to house everybody.
I mean, at the same time, and we don't have a Menzies government who believes, you know, that every homeowner is a liberal voter. So I think politically we're very different now too, don't you think? We are, but I do think we are hitting the limits of what we can do within the
bounds of the orthodoxies that we've accepted over the past couple of decades.
I was talking before about how concerned I am that the government is trumpeting all this housing affordability action that it's taking and how are people going to feel in five years' time if they haven't experienced the benefits of that in their own lives and they're not seeing the impacts of that.
I think it's a big part of why people are becoming more and more disgruntled. It's a big part of why they're turning away from politicians who they feel have been failing them for a really long time. And so I do think we need to start looking at something a bit more...
you know, a bit more radical and maybe thinking outside the box about what the role of government is. And it's interesting because we don't question in other areas.
The government has announced in the past couple of months that it's going to spend a greater proportion of GDP on defence spending and there's been an enormous amount that's gone into defence. defence of the past couple of years.
That's not my area, so I'm not going to say whether I think that's good or bad. But, you know, governments can find the money when they decide to prioritise something. I mean, I remember when AUKUS was announced, Josh Frydenberg was asked, is this affordable?
And his answer was, everything is affordable if you decide you can afford it. And I think the government has decided that it's not going to spend this money on housing its own people. And I think... You know, we've seen successive governments and we're seeing a real kind of crunch point around this now.
They're paying the price for that in terms of just lost trust.
I guess if I was working in the development industry, I'd be like, well, we're not, obviously, but the... It's so hard to make a profit. We're cutting costs everywhere we can. We've got to be super efficient to deliver efficiently.
And I guess it's taken years to get the team together. And we've got to get the staff. And we've got to train them. And so, yeah, they could start it. But they're going to have challenges. It's like a business. And the government has...
you know, done lots of different infrastructure spending where it goes way over budget and what they expected. And I guess it's just a worry that, yeah, okay, like this is the desire to do it and absolutely start doing it.
But can you really move the needle when there's already 3 million investment properties out there, right? Like, And we've got this huge shortfall. I guess I wonder if it's a decade solution versus like a solution that we're going to see anytime soon. And if anything, the government are doing the opposite, right?
They're selling off land. They're trying to raise capital, the state governments, the federal government to fund spending. So they're not even holding onto these great sites that would be good. Or they're letting go of
you know, affordable housing in premium suburbs, because it's great for the locals, but then it's putting more affordable housing, you know, on the fringes. So it's going to, you know, not an integrated model. It's putting more affordable houses in, you know, certain pockets, like a Paris strategy versus a London strategy.
So, I mean, what's your take on that as well? Like, what are some of the mistakes the governments are making around just even just preparing for this shift?
I think it is a huge mistake to approach public and community housing as though the only way that we can get more of it is by selling off what we have. I think that's been a massive mistake.
I think part of the reason that that's been happening, though, is because the federal government is not putting in anywhere near as much money into public and community housing as it used to.
I feel like I've been nerding out on a lot of research, but again, Everybody's Home did a big piece of research on this where we looked at how much the government spent on directly investing in housing. This is the federal government in the early 80s and traced the changes.
And it now, the amount that it spends now subsidising market housing through housing
the tax the foregone revenue from the tax concessions that we were talking about a bit earlier but also things like commonwealth rent assistance that absolutely dwarfs what it spends directly building housing and so states and territories have been responding to that by making it harder to get into public housing um you know it used to be something that a lot of working people did not just people on very low incomes um at some point in their life and um you know now they're responding by having to you know
sell off existing stock when they want to invest in something new.
It's really interesting to sort of compare those two figures. But with the tax concessions given for native gearing, it's a whole picture thing though, isn't it? Because when they sell that property, they then do pay capital gains tax, which goes back to the government coffers.
But they also, potentially in a situation where they can maybe not go on the pension. So is the complete picture looked at with that sort of analysis? This is a bigger conversation than property, but I never use the phrase self-funded retiree.
It costs almost as much to subsidize people through their superannuation concessions than it does to people.
I will say that's a digression. But they're also paying capital gains tax at a discount. But it's still a fuller analysis than simply just taking one piece. I think you do have to look at the life cycle, don't you, if you're going to really put that argument forward.
Any way you slice it, it's an amount that dwarfs direct investment. So federal government, depending on the year that you're looking at, it's between $1.8 to $2.2 billion that there's been on direct provision of housing, and it's between $15 and $20 billion on support for market housing.
I think it's an interesting framing of the issue, because if you went out and asked an average person on the street, including a person who invests in property themselves, we've got $20 billion to spend on housing. How should we spend it?
I doubt anyone would come back and say, what we need is a Baroque series of tax breaks for property investors. I think most of them would say some version of let's build homes that people can actually afford. Yeah, I think that's a good point.
And so we're hopefully seeing tonight's budget one step towards that by winding back some of these tax concessions.
We now need to see them do the next part of that, which is not just bank the savings, but actually put that money in to rentals that people can afford or housing that people can afford to live in. So do you think the family home should remain a tax-free haven? Absolutely.
I'm a bit less concerned about the family home than I am about investment. I don't think it's driven the level of speculation that we've seen in investment as investment properties have. But it would be interesting.
I mean, one of the questions you asked earlier that we didn't get to was about lending behavior and whether that's something that's flown under the radar. Yeah.
You know, I'd be very interested in looking at that because I do think banks have really flown under the radar in terms of who are the culprits, who are the people who cause the housing crisis. Lots of discussion about immigrants and increasingly more discussion about investors.
But, you know, banks are making an enormous amount of money from, you know, changes in lending behaviour over the past couple of decades. And I do wonder if that isn't also part of a picture about why housing hasn't become a lot more expensive in the past couple of years. Well, that's it.
That's the elephant in the room. That's huge. And yet it is missing from almost all of the debate.
Yeah. I mean, this is our space. When I started broking in 2013, you could borrow 10, 12, 14 times your income. You could get 15 year interest only terms. You could borrow way more for investment properties than you could for owner occupy.
There was so many flaws with all the calculators across all the different banks. And, you know, if you lodged it with this bank, you'd get this and you could do this, et cetera. Like every year, like 2015, it started to get tighter and every year it has got tighter.
And so like- But what was it like in 1995?
You know, what was it like 20 years before that?
Yeah, but I don't think he had two incomes and I don't, you know, so it wasn't really this sort of, it went out of control, I think in the mid 2000s, I would say, you know, and I think, you know, access to sort of competition and more lenders.
But I would say in the last five years, there's been an explosion of non-bank lending and more and more as broker market shares gone to close to 80% now, investors are coming to them and saying, Hey, look, I want to borrow another investment property. Oh, you can't work with the banks.
But if we go to this non-bank, you can borrow more money. And that's absolutely been the case. And that's pushed into self-managed super fund lending. That's why I'm hoping tonight with the budget, they look at self-managed super fund lending.
I think if they don't, we'll see it all over Instagram tomorrow is, hey, leverage your super, buy an investment property. Because they'll be looking for some way of still selling properties and their services. And I've already seen it today, to be honest, in the media.
So I think they're going to miss a trick because a lot of people are just going to leverage their super up over the next six months because they can't do it personally. Yeah, I think lending's got tighter, but you've already let the cat out.
The horses have already bolted and a lot of people have used that additional lending to leverage up and then get the growth. But yeah, current lending's pretty tight compared to what it was. Yeah, obviously it's a big night.
Obviously it's this stuff you guys have been campaigning for, so I'm sure there's a few bottles of champagne getting popped in your hood. I agree with it in lots of ways. I do think that there's challenges with the older model. I do think there's going to be some... unintended consequences. I genuinely do.
And I think that sometimes the outcome that people want and the outcome they get is probably going to be different. But I think that the old model also hasn't worked a lot for people as well. And they're often forgotten about. So yeah, time will tell with these things.
Yeah, it's going to be a big night. Yeah, I think the challenge will be getting people and especially people in this government who've been so cautious about making big changes over the past couple of years.
If these things don't have the impact that they hope they're going to have, it would be ideal if they didn't just see that as this is a failure of the tax changes. Nobody has predicted that the tax changes on their own are going to drastically improve affordability.
hopefully they realise that there's a missing step for them in playing a role in providing some of this housing themselves.
I think there's been quite a few people that come out saying that that's the only problem. So actually, I disagree. I think plenty of people have come out saying this is a solution. And that's the sad thing, I think, because if you hang your hat on that, you're going to be sorely disappointed.
But also, if that's the only change, you kick in the can down the road and then the delay to doing anything that really is going to move the needle even further, you know? So, and I agree with you definitely that government needs to step up.
Well, apparently there's, there's lots of money to be, to be thrown at building new housing as well. We haven't even talked about build to rent in this episode because that's a small part of supposedly solution, but also governments are,
Apparently, it's not as transparent as the tax breaks given to individual investors, but there's apparently quite a few tax breaks handed out to institutions to get into that space too. So it'd be interesting to see some analysis as to, well, what's been taken away from individual investors who have supported tax breaks.
the country with Ventral Stop for the last four decades and being given to institution now. It's like, you've done your job now. See you later. We're going to go and support the big end of town. So there's a whole other conversation there, I'm sure, that we could have. Yeah, totally.
Could I quickly, very quickly, give my few cents on that? Yeah, please do. Build to Rent in Australia and in many other parts of the world is a pretty premium product, actually, not something that's bringing down the cost of rents. And I think the goodies that that sector is going to get
gets, should be tied to an affordability outcome. You know, you can't increase rents more than a certain amount if you want like taxpayer support, you know. Yeah. Yeah, it should be.
And there needs to be more transparency around that too because that's very opaque and I feel that that's a bit sneaky personally. Yeah. Yeah, I think if you're an institutional investor like that and you're purporting to do, you know, all of the language around it is as though it's doing something really good.
And I think, well, I think if you're going to get goodies from taxpayers, you ought to be delivering some kind of affordability outcome or even a security outcome. You know, we've seen that some of these build-to-rent landlords actually evict people pretty freely when part of the...
value proposition was that it would be a bit more secure. So, you know, we should be looking at all of that. It's been a very interesting chat, May. Thank you so much for coming on.
I know that in a few hours, we're going to know the answers to some of the questions that we've been skirting around in this episode. So thank you for your time. Thanks for having me. Thank you.
If you have a question that you'd like us to answer in an upcoming Q&A episode, you can send us a voicemail or written question via the website, theelephantintheroom.com.au, or you can email us directly at questions at theelephantintheroom.com.au. If you like what you're hearing, please share this episode with others you feel would benefit.
And while you're at it, why not leave us an iTunes review? Five stars would be great. I know that sounds a bit cringy, but we have it on good authority that every review helps make it easier for other people to find out about us and hear what our amazing guests have to say.
Key takeaways
- Everybody's Home research put the income needed to avoid rental stress at over $130,000 a year for a single person in a major city, and $110,000 in a regional area.
- Anglicare's rental affordability snapshot found a single person on the minimum wage could afford about one in five rentals 15 years ago, and under 1% in the latest edition.
- Listings rose about 10% last year and affordability still fell, which Azizi uses to argue the problem is not a simple supply and demand equation.
- Azizi expects negative gearing changes to be heavily grandfathered, and argues that protecting existing investors can widen the inequity.
- Federal direct spending on housing was put at $1.8bn to $2.2bn against $15bn to $20bn supporting market housing.
- Chris raises the counter case: a shortfall near 600,000 homes, competition for trades, and what happens to renters if nothing replaces investor stock.
What Income Do You Need to Avoid Rental Stress?
The episode opens on a renter earning $80,000 who spends 45% of his take home pay on a two bedroom in a middle ring suburb. May Azizi, Deputy Director of Anglicare Australia and national spokesperson for Everybody's Home, says that household is no longer the edge of the problem: research the campaign ran last year found a single person in a major city would need over $130,000 a year to avoid rental stress, and $110,000 in a regional area.
Veronica Morgan pushes on the definition. Rental stress is about proportion, not dollars: rent above 30% of income counts on average or low incomes, while a very high earner has more discretion.
Anglicare's rental affordability snapshot supplies the other half of the picture. It checks every listing on realestate.com.au over a sample weekend against 14 low income household types. A single person on the minimum wage could afford about one in five rentals when the snapshot began roughly 15 years ago; in the current edition it is under 1%, and for people on Centrelink payments the figure has sat at zero year after year.
| Household situation | Figure quoted | Source named on air |
|---|---|---|
| Single person, major city | Over $130,000 a year | Everybody's Home research, to avoid rental stress |
| Single person, regional area | $110,000 a year | Same research |
| Single on minimum wage, about 15 years ago | About 1 in 5 rentals | Anglicare rental affordability snapshot |
| Single on minimum wage, latest edition | Under 1% of rentals | Anglicare rental affordability snapshot |
| Person on Centrelink payments | 0% | Snapshot, repeated year on year |
As described at 3:29, 3:45 and 20:09. Figures as stated on air.
Does Australia Have Enough Homes?
Azizi's argument is that listings and affordability have come apart. Last year the snapshot counted a 10% increase in listings and affordability still went backwards. During COVID there were roughly double the listings and it did not move either.
She also disputes that the country has too few homes. Australia built a million homes over the decade before last, which she says outstrips population growth including immigration, and at every census since the early 90s the number of homes per person has increased. Her reading is that homes are more unfairly distributed than ever, with wealthier households taking up more space. Airbnb she calls a real driver in Byron Bay or Tasmania but a symptom nationally. Population and completion numbers like these sit under the four competing scenarios SQM Research maps for the year ahead.
Veronica counters from the other side of the ledger, describing the wave of Sydney apartment building before COVID that pushed rents down across the city, and her view that landlords can only charge what the market will bear. Azizi's reply is that rents in Victoria have been stabilising rather than spiking as investors sell.
I don't want to sound glib. Homes are not like bananas. It's not just as simple as supply and demand.
May Azizi, 33:49
How Would Negative Gearing Changes Hit Renters?
The conversation was recorded on budget night, before the announcements landed, with negative gearing and the capital gains tax discount both expected to be touched. Everybody's Home has long called for the discount to be wound back, and Azizi expects the negative gearing changes to be more heavily grandfathered. Her view is that grandfathering widens the inequity by protecting existing investors and closing the drawbridge behind them.
Chris Bates presses on what happens to renters if the settings change and nothing replaces the stock. First home buyers face less competition at open homes, but people who cannot buy at all still need somewhere to rent. Azizi's answer is that renters leave the rental market too, the house does not dematerialise when an investor sells, and nobody has claimed tax changes alone would drastically improve affordability.
Both agree on the second half. Azizi argues the savings need to go into rentals people can afford rather than being banked, and worries about a budget people cannot feel ten years later.
Are Locals Priced Out of Regional Towns?
Chris describes investor lending running hard at low price points over four or five years, much of it younger buyers rent vesting at $700,000 to $900,000 and heading for the regions: Ballarat, Newcastle, Bendigo, Mildura, Townsville. His concern is that the cheaper place people move to is priced beyond what locals earn.
Azizi agrees, pointing to the same pattern in Everybody's Home's priced out report and its work on essential workers and regional rents, which found rents unaffordable for most of them. Her point is that a town does not function without people who can work in aged care, a hospital or a cafe.
It's really not their job to provide affordable housing, in my opinion. I mean, it's the government's job to do that.
May Azizi, 36:52
Where Does Federal Housing Money Go?
The sharpest numbers in the episode are the two federal spending lines. Azizi puts direct provision of housing at $1.8 to $2.2 billion depending on the year, against $15 to $20 billion supporting market housing through foregone tax revenue and payments such as Commonwealth Rent Assistance.
| Measure | Figure quoted | Period described |
|---|---|---|
| Federal direct provision of housing | $1.8bn to $2.2bn | Recent years, varies by year |
| Federal support for market housing | $15bn to $20bn | Same comparison |
| Federal share of new home building | About 1 in 4 new builds, about 30,000 homes a year | At the post war high point |
| Renters renting from government | About 1 in 3 | Up to the early 80s |
| Housing accord target for private builders | 1.2 million homes | Current federal target |
As described at 12:08, 39:02, 39:34 and 47:42. Figures as stated on air.
Chris is not convinced the state can move the needle at that scale, citing a shortfall he puts near 600,000 homes against 11.5 million dwellings and about 3 million investment properties. Azizi counters that if the private sector has the workforce for a 1.2 million home target, so does the public sector.
Two threads close it out. Build to rent, which Azizi calls a premium product internationally that should have its concessions tied to an affordability outcome. And lending, where Chris recalls borrowers taking 10 to 14 times income in 2013, while Azizi says banks have flown under the radar in this debate.
I doubt anyone would come back and say, what we need is a Baroque series of tax breaks for property investors.
May Azizi, 48:11
Weighing Up What Tax Change Means for Your Portfolio
This episode maps out the arguments on both sides of negative gearing, the capital gains tax discount and where rental stock comes from next. If you are weighing what any of it means before you take on an investment property loan, our team can talk it through with you.
Investment Property Mortgage BrokerSources referenced: The Elephant in the Room, episode 438, "Can Housing Be Fixed Without Hurting Investors?", released 24 May 2026. Host: Chris Bates (Alcove). Co-host: Veronica Morgan. Guest: May Azizi, Deputy Director of Anglicare Australia and national spokesperson for Everybody's Home. Figures are quoted as stated on air and have not been re-checked against current data.
Press play on these